Market Daily: Trump unveils Russian diesel deal as telecoms slide on SpaceX spectrum purchase
Trump unveils a Russian diesel deal under a US Treasury licence. The FTSE 100 closed up 1.06 per cent on 9 October as telecoms fell on SpaceX's spectrum move.
MARKET DAILY · MARKETS, TECHNOLOGY AND CRYPTO · 10 October 2026
President Donald Trump said on Friday 9 October that Russia had agreed to supply diesel to the United States and world markets, and the US Treasury issued a licence the same day permitting the sale and import of Russian-origin diesel. The FTSE 100 closed 1.06 per cent higher on Friday, while telecoms shares in London and New York fell after SpaceX agreed to buy nationwide low-band spectrum for its Starlink Mobile service. Brent crude settled at $104.72 a barrel, up 0.42 per cent on the day. This is Cristoniq’s Market Daily for Saturday 10 October 2026. Markets are closed this weekend, so equity, bond, currency and commodity figures are Friday’s closes; crypto figures are live and carry their observation time.
The day ahead
No UK or US statistical releases, government bond auctions or FTSE 350 company updates are scheduled for Saturday 10 October. Crypto markets trade through the weekend, and the Fear and Greed Index reading for 10 October is 64, labelled “Greed”, up from 59 on 9 October. The index blends volatility, trading volume, social media and other signals, with 0 meaning extreme fear and 100 extreme greed; our Crypto Decoded guides explain how to read it.
The next trading day is Monday 12 October. In the United States it is the Columbus Day holiday: the New York Stock Exchange does not list it as a holiday, so share trading runs as normal, but the Securities Industry and Financial Markets Association recommends a full close for the US bond market, and the Federal Reserve has moved its daily and weekly statistical releases for that day to Tuesday 13 October. In London, Hays is due to publish a trading statement, Pennon’s shares are marked ex-rights at 8:00 am BST under the £550 million rights issue covered in our 8 October edition, and Aberdeen’s placing of 52 million Standard Life shares is due to settle.
UK Market Update
The FTSE 100 closed at 10,552.10 on Friday 9 October, up 110.50 points, or 1.06 per cent, from Thursday’s 10,441.60, ending two days of losses. The FTSE 250 closed at 24,213.80, up 269.90 points or 1.13 per cent from 23,943.90. From the Friday 2 October close to the Friday 9 October close, the FTSE 100 rose 0.86 per cent from 10,462.00 and the FTSE 250 rose 0.08 per cent from 24,194.20.
Software and data companies led the index after Thursday’s sell-off on worries about artificial intelligence disrupting their business models. Relx was the biggest riser, up 125.0p at 2,720.0p, or 4.8 per cent, followed by Antofagasta, up 165.0p at 3,770.0p, or 4.6 per cent, on firmer metals prices, Sage Group, up 44.0p at 1,071.5p, or 4.3 per cent, and Experian, up 108.0p at 2,682.0p, or 4.2 per cent. Telecoms were the day’s weak spot after SpaceX’s spectrum purchase, discussed in the US section below, raised concerns about competition from satellite-based mobile services. Airtel Africa was the biggest faller, down 19.4p at 290.2p, or 6.3 per cent, with Vodafone down 6.05p at 118.35p, or 4.9 per cent, and BT Group down 4.70p at 192.75p, or 2.4 per cent. Russ Mould of AJ Bell said in the closing market report that markets “continue to move like a yo-yo”.
In the FTSE 250, Morgan Advanced Materials rose 9.4 per cent after RBC upgraded the shares to “outperform” with a 330p target, citing a possible sale of its thermal business. Ocado rose 6.7 per cent on a report that Australian grocer Coles Group may trial its robots in a Melbourne store. SSP fell 4.1 per cent after forecasting full-year underlying operating profit of £230.0 million, below market expectations.
Airtel Money’s London debut. Airtel Mobile Commerce, the mobile money business of Airtel Africa, began conditional dealings on the London Stock Exchange on Friday 9 October after pricing its initial public offering at 196p a share on 1 October, giving a market value of about £5.3 billion. Conditional dealings mean trades are settled only once the shares are formally admitted; unconditional dealings are due to start at 8:00 am BST on Wednesday 14 October. The shares closed their first conditional session at 184.26p, 6.0 per cent below the offer price. The float is the largest in London since 2021 and is a sale of existing shares by current shareholders, so Airtel Africa itself raises no new money; it stays on as a long-term strategic shareholder.
US Market Update
The S&P 500 closed at 7,811.54 on Friday 9 October, up 46.18 points or 0.59 per cent from Thursday’s 7,765.36, and within eight points of its record close of 7,818.93 set on Tuesday 6 October. The Nasdaq Composite closed at 27,366.17, up 172.83 points or 0.64 per cent, recovering part of Thursday’s 1.25 per cent fall, and the Dow Jones Industrial Average closed at 51,654.95, up 423.31 points or 0.83 per cent. From the Friday 2 October close to the Friday 9 October close, the S&P 500 rose 1.15 per cent, the Nasdaq 0.64 per cent and the Dow 0.93 per cent. Stocks reached their session highs after Trump’s diesel announcement.
SpaceX buys low-band spectrum. SpaceX said on Thursday 8 October that it had agreed to acquire Grain Management’s nationwide 800 megahertz spectrum portfolio for its Starlink Mobile service. Financial terms were not disclosed and the purchase needs approval from the Federal Communications Commission. Low-band spectrum carries signals further and penetrates buildings better than the higher frequencies satellite services have used, which is why investors read the deal as a step towards SpaceX competing directly for mobile customers rather than only filling coverage gaps for existing carriers. Elon Musk called it “the last critical piece of the spectrum puzzle needed for SpaceX to provide complete phone coverage in America”, as quoted in the London closing report. At Friday’s New York close, T-Mobile US was down 13.3 per cent at $148.58, AT&T 10.8 per cent at $22.18 and Verizon 10.1 per cent at $41.65, while SpaceX shares closed up 1.25 per cent at $162.57.
Delta cuts its full-year outlook. Delta Air Lines reported third-quarter results on Friday 9 October in a filing with the Securities and Exchange Commission. Adjusted earnings per share were $1.72 on adjusted revenue of $17.6 billion and an adjusted operating margin of 9.4 per cent. Adjusted fuel expense was $4.14 billion at an adjusted $3.61 a gallon. For the December quarter Delta expects revenue growth of about 20 per cent year on year and earnings of $1.15 to $1.65 a share, and it now guides to full-year 2026 earnings of $5.10 to $5.60 a share, down from the $6.50 to $7.50 range it reaffirmed in July. Chief executive Ed Bastian said: “Demand remains strong, supported by consumers’ growing preference for experiences and travel.” The cut matters because it shows higher jet fuel costs, a consequence of the oil price, outrunning Delta’s ability to pass them on through fares.
Consumer sentiment weakens. Following up on the release flagged in our 9 October edition, the University of Michigan’s preliminary October consumer sentiment index fell to 46.3 from 48.1 in September. The current conditions index dropped to 44.7 from 50.9 while expectations edged up to 47.3 from 46.3. Year-ahead inflation expectations rose to 4.7 per cent from 4.6 per cent and long-run expectations to 3.5 per cent from 3.4 per cent. Survey director Joanne Hsu said: “Frustration over cost-of-living continues to mount.” The final October reading is due on Friday 23 October at 10:00 am EDT (15:00 BST).
Global Markets
Trump announces Russian diesel supplies. In a post on Truth Social on Friday 9 October after a call with Russian President Vladimir Putin, Trump wrote that Russia “will immediately supply over 300,000 Tons of Diesel Fuel to the American and Global Marketplace”, with “another 500,000 Tons during the month of November” and “1,000,000 Tons immediately thereafter”, and that Russia would eventually deliver “another 3 million tons of diesel fuel” depending on the condition of its refineries. The Treasury’s Office of Foreign Assets Control issued Russia-related General License 135 the same day, authorising transactions related to the sale, delivery, offloading and importation of diesel fuel of Russian origin. A general licence lets anyone carry out the covered transactions without applying for individual permission; this one covers diesel only and leaves other Russia-related sanctions in place. The Kremlin’s account of the call said the two leaders spoke for an hour and a half and that Russia “reaffirmed its readiness to supply oil and oil products to the American and world markets”. Ukrainian President Volodymyr Zelenskyy wrote on X: “Gifts to Putin will not bring peace or any benefit to the civilized world.”
The background is a diesel squeeze on both sides of the Atlantic. The war that began on 28 February 2026, when the United States and Israel launched strikes on Iran, led to the effective closure of the Strait of Hormuz and a surge in crude prices, and Ukrainian strikes on Russian refineries have cut Russia’s own diesel exports. The US average retail diesel price was $6.27 a gallon on Friday, about 70 per cent higher than before the war, with the midterm elections due on 3 November. On Thursday Trump had said the United States would not attack Iran before the midterms, which we covered in our 9 October edition.
Elsewhere, Germany’s DAX closed at 25,087.27 on Friday 9 October, up 280.30 points or 1.13 per cent from 24,806.97, but 0.57 per cent lower than its 2 October close of 25,231.20. Japan’s Nikkei 225 closed at 69,030.92, down 0.02 per cent from 69,042.11 on Thursday and up 1.06 per cent on the week from 68,309.46. Mainland Chinese markets reopened on Thursday 8 October after the 1 to 7 October National Day holiday.
Bonds, Currencies and Commodities
The UK 10-year gilt yield ended Friday 9 October at 5.42 per cent, down about one basis point on the day. A basis point is one hundredth of a percentage point. That followed a sharp sell-off on Thursday 8 October, when the 10-year yield touched 5.53 per cent during the session, its highest since July 2007, and the 30-year yield reached 6.05 per cent, the highest since 1998, as oil jumped. The 30-year yield stood at 5.94 per cent on Friday. Higher gilt yields raise the cost of government borrowing and of new fixed-rate mortgages priced off them. The Bank of England held Bank Rate at 3.75 per cent on 17 September by six votes to three, with Megan Greene, Catherine Mann and Huw Pill preferring a rise to 4 per cent.
The US 10-year Treasury yield closed at 5.24 per cent on Friday 9 October, from 5.22 per cent on Thursday and 5.28 per cent at the 2 October close, after a week in which it reached levels not seen since 2002 with a 5.31 per cent close on Monday 5 October. The Federal Reserve’s federal funds target range is 3.75 to 4.00 per cent, raised by a quarter point on 16 September by a 12 to 0 vote; the committee next meets on 27 and 28 October.
Sterling closed at $1.3234 at 17:00 New York time on Friday 9 October, from $1.3229 on Thursday and $1.3240 on Friday 2 October. The euro closed at $1.1206, from $1.1215 on Thursday and $1.1256 a week earlier, a fall of 0.44 per cent on the week.
Brent crude futures settled at $104.72 a barrel on Friday 9 October, up 0.42 per cent from $104.28 on Thursday and 2.42 per cent above the 2 October settlement of $102.25. WTI crude settled at $91.85, up 0.39 per cent from $91.49 and up 0.81 per cent on the week from $91.11. COMEX gold futures settled at $4,216.30 a troy ounce, up 1.43 per cent from $4,157.00 and 1.30 per cent higher on the week from $4,162.30. COMEX copper futures settled at $6.6425 a pound, up 1.89 per cent from $6.519 and 2.32 per cent higher on the week from $6.492.
Crypto
Bitcoin was $82,521 at 04:59 BST on Saturday 10 October, up 0.19 per cent over 24 hours, with a 24-hour range of $82,180 to $83,398. It remains 34.5 per cent below its record of $126,080 set on 6 October 2025. Ethereum was $2,489.01, down 0.11 per cent; XRP was $1.40, up 0.58 per cent; Solana was $109.62, down 0.66 per cent; and Chainlink was $12.80, down 0.32 per cent. The Fear and Greed Index reads 64, “Greed”, for 10 October, up from 59 on 9 October.
CRYPTO MARKET PICTURE · FIXED SNAPSHOT
Five crypto assets, one clear view
| Asset | USD price | 24h change | Magnitude (0 to 1 per cent) |
|---|---|---|---|
| BTC Bitcoin |
$82,521.00 | +0.19 per cent | |
| ETH Ethereum |
$2,489.01 | -0.11 per cent | |
| SOL Solana |
$109.62 | -0.66 per cent | |
| XRP XRP |
$1.40 | +0.58 per cent | |
| LINK Chainlink |
$12.80 | -0.32 per cent |
Powered by CoinGecko. Retrieved 10 Oct 2026, 05:00 BST. Provider observation times: BTC 10 Oct 2026, 04:59 BST; ETH 10 Oct 2026, 04:59 BST; SOL 10 Oct 2026, 04:59 BST; XRP 10 Oct 2026, 04:59 BST; LINK 10 Oct 2026, 04:59 BST. Bars compare the size of changes on a shared 0 to 1 per cent scale, not prices or capitalisation. Signs show direction. This selected crypto sample is not a picture of all crypto assets or wider financial markets; these archived quotes do not update.
Mashinsky banned in New York. New York Attorney General Letitia James announced on Friday 9 October a settlement that permanently bars Alex Mashinsky, co-founder and former chief executive of the collapsed lending platform Celsius Network, from working in the securities, commodities and cryptocurrency industries. The settlement secures up to $35 million in conditional payments: $25 million to New York if he fails to forfeit a further $10 million to the federal government on top of assets already forfeited under his plea agreement, and $10 million if he does not serve his full 12-year federal prison sentence. The office said it sued Mashinsky in 2023 for defrauding investors including more than 26,000 New Yorkers, and that Celsius creditors have so far received more than $3.4 billion through the bankruptcy. James said: “I will not allow scammers to use cryptocurrencies to prey on unsuspecting New Yorkers.” The case matters for investors because it closes the last major civil action against Mashinsky and adds a state ban to the federal restrictions already in place.
CFTC moves on event contracts. The Commodity Futures Trading Commission on Friday 9 October proposed a change to the definition of “swap” to expressly include event contracts, including those based on sports, politics, cultural and weather events, the products offered by prediction markets. Chairman Michael Selig said these are “commodity derivatives squarely within the CFTC’s regulatory remit”. This is a proposal, not a rule in force: it takes effect only after a 30-day comment period following publication in the Federal Register and a further vote. Separately, the agency issued an interim final rule stating that casino-style gambling products, including sportsbook and casino game wagers, fall outside the swap definition; it takes effect on publication, with 30 days for comment. Selig said: “Casino-style gambling products are not derivatives.” Together the two steps draw a line between contracts the CFTC claims as federal derivatives and wagers it leaves to state gambling regulators.
AI, Technology and Investor Tools
The SpaceX spectrum purchase described above was the week’s biggest technology story for investors. Two days before the Grain Management deal, on Tuesday 6 October, the Federal Communications Commission granted in part SpaceX’s application for a new 15,000-satellite direct-to-device constellation, deferring a decision on some of the frequency bands it had asked for. The combination of nationwide low-band spectrum and a much larger satellite fleet is what the carriers’ shareholders were reacting to on Friday: a service that could sell phone plans directly rather than wholesale coverage to existing networks. The spectrum deal is not yet complete and depends on FCC approval.
Friday’s rebound in software and data shares, in London and on the Nasdaq, reversed part of Thursday’s fall that followed the Financial Times report on OpenAI’s annualised revenue, covered in our 9 October edition. Relx, Sage and Experian were among the FTSE 100’s top five risers on Friday, and the Nasdaq Composite recovered 0.64 per cent after losing 1.25 per cent on Thursday.
What to Watch Next
- Monday 12 October: US bond market closed for Columbus Day (SIFMA full-close recommendation); US stock exchanges open. Hays trading statement. Pennon shares go ex-rights at 8:00 am BST. Aberdeen’s Standard Life placing settles.
- Tuesday 13 October: Fed Governor Christopher Waller takes part in a discussion on AI at the Bloomberg New Economy Forum in New Delhi at 3:45 am EDT (08:45 BST). JPMorgan Chase third-quarter results at about 7:00 am EDT (12:00 BST), with the earnings call at 8:30 am EDT (13:30 BST), opening the US bank reporting season. US Treasury auctions of $95 billion of 13-week and $82 billion of 26-week bills close at 11:30 am EDT (16:30 BST), and $95 billion of 6-week bills at 1:00 pm EDT (18:00 BST).
- Wednesday 14 October: Airtel Mobile Commerce unconditional dealings begin at 8:00 am BST. Fed Vice Chair for Supervision Michelle Bowman speaks at the IIF Annual Membership Summit in Bangkok at 5:40 am EDT (10:40 BST). US consumer price index for September at 8:30 am EDT (13:30 BST). Fed Beige Book at 2:00 pm EDT (19:00 BST). China’s September inflation data are also due on 14 October.
- Thursday 15 October: UK GDP monthly estimate for August at 07:00 BST. Fed Chair Kevin Warsh in a fireside chat with IMF Managing Director Kristalina Georgieva in Bangkok at 11:30 pm EDT (04:30 BST on Friday 16 October).
- Friday 16 October: US industrial production for September at 9:15 am EDT (14:15 BST).
- Monday 19 October: The CMA must deliver its report on BT’s completed acquisition of TalkTalk to the Secretary of State for Digital, Culture, Media and Sport, Lisa Nandy, by 5pm; the invitation to comment closed on 9 October.
- Tuesday 20 October: UK labour market overview at 07:00 BST.
- Wednesday 21 October: UK consumer price inflation for September at 07:00 BST.
- Friday 23 October: Final University of Michigan October consumer sentiment at 10:00 am EDT (15:00 BST).
- Monday 26 October: Latest time for acceptance and payment under Pennon’s rights issue, 11:00 am GMT, with the result due by 8:00 am on 27 October.
- Tuesday 27 and Wednesday 28 October: Federal Open Market Committee meeting.
- Tuesday 10 November: US CPI for October at 8:30 am EST (13:30 GMT). Thursday 12 November: UK GDP for September at 07:00 GMT. Wednesday 18 November: UK CPI for October at 07:00 GMT.
Explore the live Bitcoin chart and Fear & Greed indicator
Optional live context
The briefing above is a fixed, dated snapshot. These provider displays update independently and may show different values. They do not change the article’s archived figures.
Bitcoin chart: daily candles, US dollars
TradingView · Bitstamp BTC/USD · London timezone. Each candle shows one day’s opening, high, low and latest or closing price. The latest candle is still forming. This is one exchange, not CoinGecko’s aggregated quote. Check the provider’s displayed time and data status.
The chart loads separately and may take a moment to appear. If it stays blank or looks stale, use the source-chart link below or hide the chart area. The dated market table remains readable without it.
Open the Bitcoin source chart on TradingView ↗
Latest provider Fear & Greed indicator
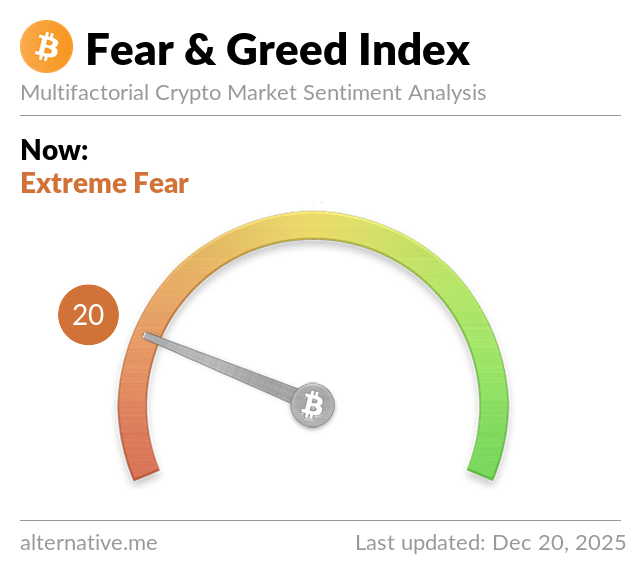
Sentiment image unavailable. Use the provider link above; the dated reading in the article remains available.