Market Daily: Pennon launches £550m rights issue as most Fed officials say another rate rise would likely be appropriate
Pennon launches a £550m rights issue and cuts its dividend, Fed minutes say another rate rise would likely be appropriate, and the IEA speeds up oil releases.
MARKET DAILY · MARKETS, TECHNOLOGY AND CRYPTO · 8 October 2026
Updated 16:55 BST, 8 October 2026
Digitally generated conceptual header, not a real event or a forecast. News cut-off 8 Oct 2026, 05:00 BST; sources checked through 8 Oct 2026, 05:00 BST; the fixed crypto observations are timed separately below.
Pennon, the owner of South West Water, launched a £550 million rights issue and cut its dividend on Wednesday, while minutes of the US Federal Reserve’s September meeting showed that most participants thought another rate rise “would likely be appropriate” by the end of the year. Members of the International Energy Agency agreed to speed up the release of the roughly 100 million barrels still outstanding from the 400 million barrel emergency stock action agreed in March, and the US Treasury sold 10-year notes at the highest yield since 2000.
This is Cristoniq’s Market Daily for Thursday 8 October 2026. Sources were checked up to 05:00 BST on 8 October. Figures taken from data providers are given with the provider and observation time. Figures quoted from news reports carry the time or session the report gave. Unless a source is named for them, percentage and point changes are Cristoniq calculations from the named provider’s figures. Weekly changes run from the Friday 25 September close to the Friday 2 October close; week-to-date changes run from the Friday 2 October close to the Wednesday 7 October close. Index closes are from Yahoo Finance; other providers may differ by a few points. A currency close in this edition is Yahoo Finance’s 17:00 New York rate for the stated date. This edition is general information for educational purposes, not personalised investment advice; it does not take account of any reader’s circumstances, and past moves are not a guide to future ones.
The day ahead
In London, Tesco published its interim results for the 26 weeks to 29 August on the morning of Thursday 8 October, after our cut-off. According to ESM Magazine’s report of the announcement, adjusted operating profit rose 6.3 per cent to £1.78 billion, sales excluding VAT and fuel rose 2.0 per cent to £33.8 billion, UK like-for-like sales (sales at stores open in both periods) rose 1.3 per cent in the second quarter after 1.8 per cent in the first, and Tesco lifted the bottom of its full-year adjusted operating profit guidance to a range of £3.15 billion to £3.3 billion from £3.0 billion to £3.3 billion, while adding £200 million to its share buyback to take it to £950 million. Informa’s new shares from Tuesday’s placing are expected to begin trading at 8:00 am BST on or around 8 October, as covered in our 7 October edition.
In the United States, a report by 24/7 Wall St carried by Yahoo Finance on 6 October said the Treasury sells $22 billion of 30-year bonds on 8 October; TreasuryDirect’s upcoming auctions data confirm the $22 billion 30-year bond auction on 8 October, with competitive bids closing at 1:00 pm EDT (18:00 BST).
On the crypto side, the Fear and Greed Index reading for 8 October is 64, labelled “Greed”, down from 71 on 7 October. The index is Alternative.me’s daily blend of volatility, volume, social media and other signals, with 0 meaning extreme fear and 100 extreme greed.
UK Market Update
The FTSE 100 closed at 10,458.50 on Wednesday 7 October, according to Yahoo Finance (observed 16:35 BST). That is 83.20 points, or 0.79 per cent, below Tuesday’s close of 10,541.70, ending a run of three daily gains. The FTSE 250 closed at 24,036.80 per Yahoo Finance (observed 16:40 BST), down 178.50 points or 0.74 per cent from 24,215.30. On a Friday-to-Friday basis, the FTSE 100 fell 2.18 per cent from 10,695.30 on 25 September to 10,462.00 on 2 October, and the FTSE 250 fell 0.28 per cent from 24,261.10 to 24,194.20 (Yahoo Finance daily closes). Week to date, the FTSE 100 is 0.03 per cent below its 2 October close of 10,462.00 and the FTSE 250 is 0.65 per cent below 24,194.20.
A Yahoo Finance UK closing report at 17:20 BST on Wednesday put the FTSE 100 at 10,458.50, down 0.8 per cent, and named Prudential (down 43.2p at 881p, or 4.7 per cent), Standard Chartered (down 102p at 2,151p, or 4.5 per cent) and HSBC (down 64.2p at 1,408p, or 4.4 per cent) among the biggest fallers, with JD Sports (up 3.16p at 83.5p, or 3.9 per cent), Reckitt Benckiser (up 129p at 5,106p, or 2.6 per cent) and Haleon (up 8.4p at 342.4p, or 2.5 per cent) among the risers (percentages from the report’s prices). The report set the bank falls against the day’s bond sell-off and said JD Sports rose after Frasers Group took an 8.8 per cent stake in Under Armour. HSBC fell after the Financial Times reported that the bank plans sweeping job cuts in its UK wealth management business as it uses artificial intelligence to serve wealthy clients; an Investing.com account of the FT story carried by Yahoo Finance at 5:50 am BST on 7 October said about half of management and specialist roles could go and the number of financial advisers could fall by about 70 per cent, with affected staff expected to leave at the end of October. The closing report quoted an HSBC spokesperson: “We are currently in a consultation period.” Pennon closed at 361.20p on Wednesday against 452p on Tuesday, a fall of 20.1 per cent (Yahoo Finance UK daily closes), having been down 15.4 per cent by 08:23 GMT according to a Reuters report carried by Investing.com.
Pennon rights issue. Pennon launched a fully underwritten £550 million rights issue on Wednesday 7 October, according to its stock exchange announcement, carried by Investegate. A rights issue lets existing shareholders buy new shares in proportion to their holding, usually at a discount; “fully underwritten” means banks have agreed to buy any shares not taken up, and here Barclays and Morgan Stanley act as joint global co-ordinators and joint bookrunners. The announcement sets the terms: 220,257,997 new shares at 250p, seven for every 15 held, a 35.5 per cent discount to the theoretical ex-rights price of 387.73p (the share price adjusted for the new shares, known as TERP). It gives the closing price on 6 October as 452p, so the issue price is a 44.7 per cent discount to that. Pennon says the proceeds will support increased investment in its regulated water businesses, improved operational performance and the additional growth available through Ofwat’s cost change process; Proactive’s report at 7:44 am BST described this as a strategic reset while maintaining sustainable gearing through the AMP8 regulatory period to March 2030. On the dividend, the announcement rebases the total payout for 2026/27 to about £125 million, compared with £138 million for 2025/26; per share, that is around 18p, about 30 per cent lower. The shares are marked ex-rights at 8:00 am on 12 October, the latest time for acceptance and payment is 11:00 am on 26 October, and the result is due by 8:00 am on 27 October. Why it matters: shareholders who do not take up their rights, or sell them, will see their stake diluted by the new shares, and the dividend cut lowers the income the shares pay from this financial year. Our Investing Basics section explains how rights issues and discounts work.
US Market Update
According to Yahoo Finance, the S&P 500 closed Wednesday at 7,801.77 (observed 16:55 EDT, 21:55 BST), down 0.22 per cent from Tuesday’s record close of 7,818.93. The Nasdaq Composite closed at 27,538.69 (Yahoo Finance, observed 17:15 EDT, 22:15 BST), down 0.22 per cent from 27,599.79. The Dow Jones Industrial Average closed at 51,179.87 (Yahoo Finance, observed 16:00 EDT, 21:00 BST), down 0.66 per cent from 51,521.28. In the week to Friday 2 October, the S&P 500 fell 0.27 per cent, the Nasdaq rose 0.45 per cent and the Dow fell 1.26 per cent (Yahoo Finance closes, 25 September to 2 October). Week to date, the S&P 500 is 1.02 per cent above its 2 October close of 7,722.72, the Nasdaq 1.28 per cent above 27,190.86 and the Dow 0.01 per cent above 51,176.96.
Fed minutes. The Federal Reserve released the minutes of the Federal Open Market Committee’s 15 to 16 September meeting at 2:00 pm EDT (19:00 BST) on 7 October, according to its press release. At that meeting the committee raised the federal funds target range by a quarter point to 3.75 to 4.00 per cent by a 12 to 0 vote, where it stands today; the minutes say “All members agreed to raise the target range for the federal funds rate 1/4 percentage point to 3-3/4 to 4 percent”. The minutes say “Most participants assessed that another increase in the target range for the federal funds rate would likely be appropriate by year end.” On the reasoning, they say “Participants generally emphasized that inflation remained elevated while the labor market appeared to be near full employment, with some signs of strengthening, and that economic activity was expanding at a solid pace.” On energy, “Many participants assessed that the longer energy prices remained elevated, the greater the risk that cost increases in certain sectors could lead to broader price pressures.” For comparison, the Bank of England’s Bank Rate is 3.75 per cent, held by six votes to three on 17 September according to the Bank’s minutes, with three members preferring a rise to 4 per cent. Why it matters: the minutes record views held on 16 September, not a decision; the next FOMC decision is due on 28 October. The minutes themselves tie the energy-price concern to geopolitics: they say asset prices were affected by “an escalation of geopolitical tensions that pushed up energy prices”, that near-term inflation compensation rose “largely reflecting movements in oil prices”, and that the European Central Bank raised its policy rate “citing continued inflationary pressures from the Middle East conflict”. The conflict is the war with Iran that began with US and Israeli strikes on 28 February 2026, as Al Jazeera reported on 7 September.
Constellation Brands. The brewer of Corona and Modelo in the US reported second-quarter results for its fiscal 2027 (FY27, the financial year ending in February 2027) in an earnings release filed with the SEC. For the quarter ended 31 August 2026 the company reported net sales of $2,633.0 million and comparable earnings per share (EPS, profit divided by the number of shares, on the company’s adjusted basis) of $3.74, with beer net sales up 5 per cent. The company says it expects FY27 comparable EPS of $11.20 to $11.90 and reported EPS of $11.85 to $12.55, with free cash flow of $1.6 billion to $1.7 billion. The company’s advance notice said the results would be posted after the US close on 6 October with a call at 8:00 am ET (13:00 BST) on 7 October. Yahoo Finance’s market report for Wednesday, last updated at 21:03 BST, said the shares were down about 5 per cent on the day despite net sales beating analysts’ expectations. Investing.com reported on the evening of 6 October that the outlook was the reason: the company kept its FY27 comparable EPS range of $11.20 to $11.90, and the $11.55 midpoint was below the $11.72 analyst consensus the report cited.
Global Markets
European shares slipped early on Wednesday after three days of gains. A Reuters report carried by Investing.com said the STOXX 600 was down 0.4 per cent at 633.98 points by 08:23 GMT on 7 October, with technology and mining sectors leading the declines, as higher oil prices and rising global bond yields weighed. Reuters said French bond spreads widened on lingering concerns about France’s fiscal position; a spread is the gap between one country’s bond yield and another’s, usually Germany’s. By the close, a Yahoo Finance UK report at 17:20 BST said the DAX in Frankfurt and the CAC 40 in Paris had both fallen 1.4 per cent as the bond sell-off intensified, and a Reuters report carried by Investing.com, updated on the evening of 7 October, said the STOXX 600 ended 1 per cent lower, giving up most of the gains of the previous three sessions. In Asia on Thursday morning, Yahoo Finance’s five-minute chart data put the Nikkei 225 at 69,252.58 at 05:00 BST, 1.1 per cent below Wednesday’s close of 70,035.71, and the Hang Seng at 23,963.31, 0.7 per cent below 24,130.50; these are mid-session values, not closes. The euro’s fall on the same concerns earlier in the week is covered in our 6 October edition.
IEA speeds up stock release. Members of the International Energy Agency (IEA), the Paris-based body that coordinates emergency oil stocks among industrialised countries, agreed on 7 October to accelerate the release of the roughly 100 million barrels still outstanding from the 400 million barrel collective action agreed in March 2026, Reuters reported in a story carried by GV Wire. Reuters quoted IEA executive director Fatih Birol: “Member governments expressed support for accelerating the oil stock releases announced in the Collective Action of March 2026 with a view to completing them as soon as possible.” Members also backed prioritising diesel “to the extent possible, given the current tightness in diesel markets”, Reuters said. The National reported that about 325 million barrels have already been released under the March agreement, that members still hold roughly 1.1 billion barrels of emergency stocks, including over 200 million barrels of diesel, and that G7 countries agreed to release 100 million barrels of diesel and other reserves through the IEA; it quoted Mr Birol as saying “The IEA stands ready to release more of these stocks to the market if and when required.” Why it matters: this speeds up delivery of barrels already promised rather than adding new ones, and prioritising diesel targets the fuel The National describes as tight; none of it guarantees lower prices.
Bonds, Currencies and Commodities
Gilts. A Yahoo Finance UK closing report at 17:20 BST said the 10-year gilt yield was about 10 basis points higher on the day and the 30-year yield was back above 6 per cent, with signs of buying interest at that level; the report gave no closing level. The latest dated 10-year figure in our records is Investing.com’s 5.399 per cent for 6 October, down from 5.429 per cent on 5 October, as reported in our 7 October edition alongside that day’s pause in bond selling. Why it matters: every rise in gilt yields raises the interest the government pays on new borrowing, which narrows the room Chancellor John Healey has before the 28 October Budget.
US Treasuries. The US 10-year Treasury yield ended Wednesday at 5.277 per cent, according to Yahoo Finance (observed 14:59 EDT, 19:59 BST), up 0.8 basis points from 5.269 per cent on Tuesday. A basis point is one hundredth of a percentage point. In the week to Friday 2 October the yield rose 9.3 basis points, from 5.184 to 5.277 per cent (25 September to 2 October closes); week to date it is unchanged from that 5.277 per cent Friday close, after Monday’s 5.311 per cent, the highest close in Yahoo Finance’s daily series for the past two years (Cristoniq check of the provider’s data). The Reuters report carried by Investing.com said Treasuries rose in afternoon trading on Wednesday, with yields backing away from their highs, as oil prices fell and the strong $39 billion 10-year auction reassured investors that demand for long-term government debt remained intact. The 24/7 Wall St report carried by Yahoo Finance put the 30-year yield at 5.670 per cent at the 5 October close.
The Treasury’s $39 billion 10-year note auction on 7 October, flagged in our 7 October edition, drew a high yield of 5.300 per cent, the highest since November 2000, according to a report by TFTC citing TreasuryDirect data. TFTC said the auction stopped through the when-issued level of 5.317 per cent by 1.7 basis points, meaning buyers accepted a lower yield than the pre-auction market implied, and the bid-to-cover ratio (bids received divided by the amount sold) was 2.77 times against a 12-month average of 2.51. Indirect bidders, a group that includes foreign central banks, took 80.3 per cent, while primary dealers took 2.5 per cent. TFTC’s view is that the heavy reliance on foreign buyers raises questions about the sustainability of demand at these yields; that is the publication’s opinion. TreasuryDirect’s auction results data confirm the $39 billion size, the 5.300 per cent high yield and the 2.77 bid-to-cover ratio.
Currencies. Sterling closed Wednesday at $1.3213 (Yahoo Finance close for 7 October), down 0.47 per cent from Tuesday’s $1.3275. The live rate was $1.3212 at 04:59 BST on 8 October. The euro closed at $1.1201 (Yahoo Finance close for 7 October), down 0.56 per cent from $1.1264; the live rate was $1.1208 at 04:59 BST. On a Friday-to-Friday basis, sterling slipped 0.04 per cent from $1.3245 on 25 September to $1.3240 on 2 October, and the euro fell 1.22 per cent from $1.1395 to $1.1256 (Yahoo Finance closes). Week to date, sterling is 0.20 per cent below its 2 October close of $1.3240 and the euro 0.49 per cent below $1.1256.
Oil. Brent crude futures closed Wednesday at $100.20 a barrel, according to Yahoo Finance, down 0.38 per cent from $100.58 on Tuesday; the live quote was $102.20 at 04:49 BST on 8 October. WTI futures closed at $88.28 (Yahoo Finance), down 1.30 per cent from $89.44, with a live quote of $89.77 at 04:50 BST. The Reuters report carried by Investing.com said oil was higher early on Wednesday on supply concerns from a storm heading for US oil-producing regions and attacks by Yemen’s Iran-backed Houthis on Saudi Arabia; by the close both benchmarks had given up those gains on Yahoo Finance’s figures. Overnight the live quotes rose again: Brent’s $102.20 at 04:49 BST was 2.0 per cent above Wednesday’s close and WTI’s $89.77 at 04:50 BST was 1.7 per cent above. In the week to Friday 2 October, Brent fell 1.98 per cent from $104.32 to $102.25 and WTI fell 1.41 per cent from $92.41 to $91.11 (25 September to 2 October closes); week to date, Brent is 2.00 per cent below its 2 October close and WTI 3.11 per cent below.
Metals. COMEX gold futures closed at $4,140.70 an ounce (Yahoo Finance), down 1.11 per cent from $4,187.10, with a live quote of $4,162.90 at 04:50 BST on 8 October. COMEX copper futures closed at $6.5965 a pound (Yahoo Finance), little changed from $6.5945, with a live quote of $6.7325 at 04:50 BST, 2.1 per cent above the close. Week to date, gold is 0.52 per cent below its 2 October close of $4,162.30 and copper 1.61 per cent above $6.4920.
Crypto
Bitcoin was $82,724 at 04:58 BST on 8 October, according to CoinGecko, down 1.68 per cent over 24 hours, and still below the $84,000 level it fell through early on Wednesday, as noted in our 7 October edition. Ether was $2,564.12, down 1.80 per cent; XRP $1.42, down 3.38 per cent; Solana $115.69, down 2.15 per cent; and Chainlink $13.17, down 3.29 per cent (all CoinGecko, 24-hour changes to 04:58 BST). These five assets are a selection, not the whole market.
CRYPTO MARKET PICTURE · FIXED SNAPSHOT
Five crypto assets, one clear view
| Asset | USD price | 24h change | Magnitude (0 to 4 per cent) |
|---|---|---|---|
| BTC Bitcoin |
$82,724.00 | -1.68 per cent | |
| ETH Ethereum |
$2,564.12 | -1.80 per cent | |
| SOL Solana |
$115.69 | -2.15 per cent | |
| XRP XRP |
$1.42 | -3.38 per cent | |
| LINK Chainlink |
$13.17 | -3.29 per cent |
Powered by CoinGecko. Retrieved 8 Oct 2026, 05:00 BST. Provider observation times: BTC 8 Oct 2026, 04:58 BST; ETH 8 Oct 2026, 04:58 BST; SOL 8 Oct 2026, 04:58 BST; XRP 8 Oct 2026, 04:58 BST; LINK 8 Oct 2026, 04:58 BST. Bars compare the size of changes on a shared 0 to 4 per cent scale, not prices or capitalisation. Signs show direction. This selected crypto sample is not a picture of all crypto assets or wider financial markets; these archived quotes do not update.
Samsung Wallet to add USDC. Samsung said in a press release that stablecoin functionality will roll out in Samsung Wallet in the final week of October for eligible US residents aged 18 or over, with USDC as the only stablecoin supported at launch. A stablecoin is a token designed to hold a fixed value, in USDC’s case one US dollar. According to Samsung, the feature will be available at launch across 82 million US Galaxy devices, for eligible US residents aged 18 or over with a Samsung account on devices running Android 13 or higher. Bastion, which Samsung describes as a licensed stablecoin custodian, will power the cross-border payment framework, with Coinbase as sub-custodian safeguarding the USDC through Coinbase Prime Vault; Samsung says infrastructure and blockchain network support will be provided by separate partners, including Solana and Sui. Samsung says users will be able to send USDC to compatible crypto wallets internationally with no fee charged by Samsung, although receiving wallet providers or exchanges may charge fees. The “more than 60 countries” figure applies to transfers to qualifying bank accounts, where recipients receive local currency. Samsung says fees apply to those bank transfers, vary by destination and amount, and are shown in the app before the sender confirms, with delivery times varying by destination. Woncheol Chai, executive vice president and head of the digital wallet team at Samsung’s Mobile eXperience business, said: “Sending money abroad should feel as convenient as using the wallet already on your phone.” The Defiant reported the launch at 03:30 BST on 8 October. Why it matters: the feature is US-only at launch and requires identity verification, so it does not change anything for UK users yet. Our Crypto Decoded guides explain how stablecoins are backed.
AI, Technology and Investor Tools
Fed on AI investment. The Fed minutes released on Wednesday include a line on artificial intelligence: “Some participants commented that the AI buildout could cause aggregate demand to outpace aggregate supply over the medium term, putting upward pressure on inflation.” That is a concern recorded by some participants, not a committee forecast.
Webull shares. Shares in the trading platform Webull closed at $5.89 on Wednesday 7 October, down 19.1 per cent from $7.28 on Tuesday (Yahoo Finance daily closes), after the House Select Committee on China published a report titled “Free Trades, Hidden Ties: Exposing Webull’s China Links”. Its press release says the bipartisan investigation, led by chairman John Moolenaar and ranking member Ro Khanna, found that Webull “has not been transparent about its links to China”, that its data practices “expose American investors to PRC legal and surveillance risk”, and that its China-based subsidiary received Chinese government funding. The release lists five policy recommendations: codify the Securities and Exchange Commission’s cross-border task force; enact inspectability requirements for broker-dealer operations, described as a Holding Foreign Companies Accountable Act for broker-dealers; create foreign-adversary data protections for brokerage records; regulate conflicted clearing and self-custody arrangements; and bring foreign-controlled broker-dealers within the jurisdiction of the Committee on Foreign Investment in the United States (CFIUS), the body that reviews foreign investments for national security risks. Webull rejected the findings. Reuters reported on 7 October that a Webull spokesperson said: “It is deeply disappointing that the Select Committee published a report containing significant inaccuracies and unsupported conclusions without ever seeking clarification from Webull.” The spokesperson said Webull “has made every effort to cooperate with the Committee, but did not hear from them for more than 20 months before this report was released”, and that the company stores US customer data in the US. The committee’s earlier letter to Webull’s chief executive, dated 25 November 2024, raised questions about the company’s ties to Fumi Technology and Hunan Weibu and the security of US user data. Why it matters: the recommendations are proposals for Congress and regulators, not actions taken, and the company disputes the findings.
Petrol prices on Google Maps. Near real-time petrol and diesel prices from the government’s Fuel Finder scheme now appear on Google Maps, the Department for Energy Security and Net Zero and HM Treasury announced on 8 October. The release says that since February petrol stations have had to report price changes within 30 minutes or risk a fine, that around 99 per cent of all fuel sold on UK roads is now reflected in Fuel Finder, and that the data is already used by apps including Waze, PetrolPrices, the AA, Confused.com and RAC Fuel Watch. The government says comparing prices can save households that own a car around £40 a year. Why it matters: the saving is the government’s estimate of what comparing prices can achieve, not a cut in prices.
What to Watch Next
Following up on items in our 7 October edition: the Fed minutes were released at 2:00 pm EDT (19:00 BST) as scheduled and are covered above; the $39 billion 10-year auction drew a high yield of 5.300 per cent, as reported by TFTC above.
- Thursday 8 October: Tesco interim results, published this morning and covered above; US Treasury $22 billion 30-year bond auction, competitive bids close 1:00 pm EDT (18:00 BST), per TreasuryDirect.
- Wednesday 14 October: US consumer price index (CPI) for September, 8:30 am EDT (13:30 BST), per the Bureau of Labor Statistics schedule; Fed Beige Book, 2:00 pm EDT (19:00 BST), per the Fed calendar. The Beige Book is the Fed’s summary of anecdotal economic conditions from its 12 districts.
- Thursday 15 October: ONS GDP monthly estimate for August, 7:00 am BST.
- Friday 16 October: Fed industrial production and capacity utilisation, 9:15 am EDT (14:15 BST).
- Tuesday 20 October: ONS labour market overview; the September bulletin lists 20 October as the next release date. ONS economic releases are normally at 7:00 am.
- Wednesday 21 October: ONS consumer price inflation for September and public sector finances, September 2026, both 7:00 am BST.
- Friday 23 October: ONS retail sales, Great Britain, September 2026, 7:00 am BST.
- Monday 26 October: Pennon rights issue, latest time for acceptance and payment 11:00 am, per the announcement; the result is due by 8:00 am on 27 October.
- Tuesday 27 to Wednesday 28 October: FOMC meeting, with the statement at 2:00 pm EDT (18:00 GMT) and press conference at 2:30 pm EDT (18:30 GMT) on 28 October, per the Fed calendar. British Summer Time ends on 25 October, so those are 18:00 and 18:30 GMT. Chancellor John Healey’s Budget is also on 28 October; the Budget speech is usually delivered around midday in the Commons, before the Fed’s announcement, and the Treasury has not published a time.
- Thursday 29 October: US third-quarter GDP advance estimate and September personal income and outlays, both 8:30 am EDT (12:30 GMT), per the Bureau of Economic Analysis schedule.
This edition is general information for educational purposes only. It is not personalised investment advice and does not take account of your circumstances. Figures are as stated by the named providers at the stated times and may have changed.
Correction, 8 October 2026: Webull’s response to the House committee report and the committee’s five recommendations were added, and an intraday share move was replaced with the 7 October close; the Samsung Wallet details were corrected (the “more than 60 countries” figure applies to bank-account transfers, and Solana and Sui are named as partners rather than confirmed launch networks); an out-of-date “latest” gilt yield was replaced with the latest dated figure in our records, 5.399 per cent for 6 October; the source cut-off time in the introduction was corrected to 05:00 BST. The gold quote of $4,162.90 was checked against the provider’s intraday data for 04:50 BST on 8 October and stands. Also added: the GOV.UK petrol-price release, Tesco’s interim results, the IEA and Treasury context, the HSBC and Constellation explanations, Asia and week-to-date figures, and the US CPI, UK GDP, UK CPI and Pennon deadline watch items.
Explore the live Bitcoin chart and Fear & Greed indicator
Optional live context
The briefing above is a fixed, dated snapshot. These provider displays update independently and may show different values. They do not change the article’s archived figures.
Bitcoin chart: daily candles, US dollars
TradingView · Bitstamp BTC/USD · London timezone. Each candle shows one day’s opening, high, low and latest or closing price. The latest candle is still forming. This is one exchange, not CoinGecko’s aggregated quote. Check the provider’s displayed time and data status.
The chart loads separately and may take a moment to appear. If it stays blank or looks stale, use the source-chart link below or hide the chart area. The dated market table remains readable without it.
Open the Bitcoin source chart on TradingView ↗
Latest provider Fear & Greed indicator
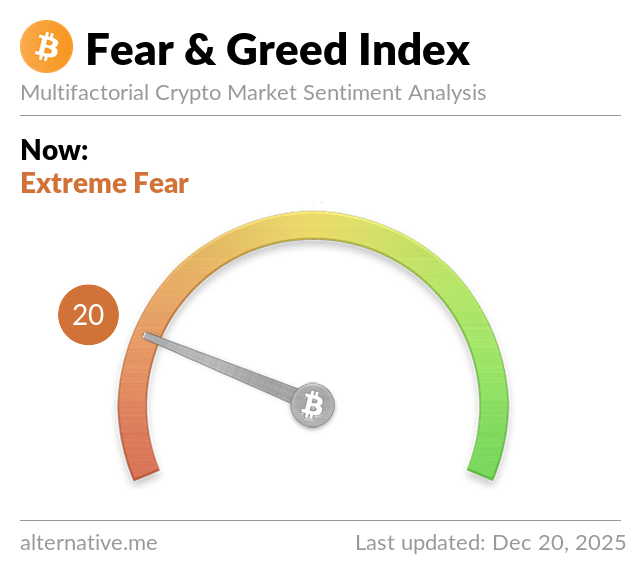
Sentiment image unavailable. Use the provider link above; the dated reading in the article remains available.