Market Daily: Nasdaq falls on OpenAI revenue report as Trump rules out Iran strikes before the midterms
Nasdaq falls after an FT report on OpenAI revenue, Trump rules out Iran strikes before the midterms, Tesco lifts profit floor and Amex agrees $350m penalty.
MARKET DAILY · MARKETS, TECHNOLOGY AND CRYPTO · 9 October 2026
Updated 07:44 BST, 9 October 2026
Digitally generated conceptual header, not a real event or a forecast. News cut-off 9 Oct 2026, 05:00 BST; sources checked through 9 Oct 2026, 05:00 BST; the fixed crypto observations are timed separately below.
The Nasdaq Composite fell 1.25 per cent on Thursday 8 October after the Financial Times reported that OpenAI’s annualised revenue is about $20 billion lower than figures circulated to investors last month. Brent crude jumped above $105 a barrel on tanker attacks in the Strait of Hormuz, then eased after President Donald Trump said the United States would not attack Iran before the 3 November midterm elections. In London, Tesco raised the bottom of its full-year profit guidance and enlarged its share buyback, and in Washington the Federal Reserve and the Office of the Comptroller of the Currency announced enforcement actions against American Express, with the bank agreeing to pay a $350 million penalty.
This is Cristoniq’s Market Daily for Friday 9 October 2026. Sources were checked up to 05:00 London time on 9 October. Figures taken from data providers are given with the provider and observation time. Figures quoted from news reports carry the time or session the report gave. Unless a source is named for them, percentage and point changes are Cristoniq calculations from the named provider’s figures. Weekly changes run from the Friday 25 September close to the Friday 2 October close; week-to-date changes run from the Friday 2 October close to the Thursday 8 October close. Index closes are from Yahoo Finance; other providers may differ by a few points. A currency close in this edition is Yahoo Finance’s 17:00 New York rate for the stated date. A basis point is one hundredth of a percentage point.
This edition is general information for educational purposes, not personalised investment advice; it does not take account of any reader’s circumstances, and past moves are not a guide to future ones.
Updated 9 October 2026: the opening sentence was split, and US jobless claims and PepsiCo’s third-quarter results were added to the US section after publication.
The day ahead
The main scheduled release is the University of Michigan’s preliminary October consumer sentiment survey, due at 10:00 am EDT (15:00 BST) according to the Surveys of Consumers website. The final September reading was 48.1, down from 51.7 in August, with year-ahead inflation expectations of 4.6 per cent, up from 4.0 per cent. The Federal Reserve’s October calendar lists no speeches by Board members on 9 October; it notes that Monday 12 October is the Columbus Day holiday, with the Fed’s daily and weekly statistical releases for that day moved to Tuesday 13 October.
In the UK, the Competition and Markets Authority’s invitation to comment on BT’s completed acquisition of TalkTalk closes on 9 October, according to the CMA case page. The page says the Secretary of State for Digital, Culture, Media and Sport, Lisa Nandy, issued a public interest intervention notice on 5 October, the CMA served a pre-emptive action order on 7 October and published it with a derogation letter on 8 October, and the CMA must deliver its report to the Secretary of State by 5pm on 19 October. A pre-emptive action order stops the buyer integrating the business while the inquiry runs.
On the crypto side, the Fear and Greed Index reading for 9 October is 59, labelled “Greed”, down from 64 on 8 October, according to Alternative.me. The index is Alternative.me’s daily blend of volatility, volume, social media and other signals, with 0 meaning extreme fear and 100 extreme greed.
UK Market Update
The FTSE 100 closed at 10,441.60 on Thursday 8 October, according to Yahoo Finance (observed 16:35 BST). That is 16.90 points, or 0.16 per cent, below Wednesday’s close of 10,458.50. The FTSE 250 closed at 23,943.90 per Yahoo Finance (observed 16:35 BST), down 92.90 points or 0.39 per cent from 24,036.80. On a Friday-to-Friday basis, the FTSE 100 fell 2.18 per cent from 10,695.30 on 25 September to 10,462.00 on 2 October, and the FTSE 250 fell 0.28 per cent from 24,261.10 to 24,194.20 (Yahoo Finance daily closes). Week to date, the FTSE 100 is 0.19 per cent below its 2 October close and the FTSE 250 is 1.03 per cent below.
Alliance News’s closing report, carried by Yahoo Finance UK at 17:29 BST, said the FTSE 100 fell as far as 10,367.25 during the session before recovering as Tesco, Imperial Brands and the oil majors rose. It named Tesco (up 24.60p at 500.40p, or 5.2 per cent) as the top riser after results that it said were well received, followed by Imperial Brands (up 126.00p at 2,614.00p, or 5.1 per cent) on its new £1.5 billion buyback, BP (up 22.80p at 584.80p, or 4.1 per cent) and Shell (up 132.50p at 3,780.50p, or 3.6 per cent) on oil price strength. Standard Life was the biggest faller, down 33.00p at 838.50p, or 3.8 per cent, after Aberdeen sold 52 million of its shares; WPP fell 12.70p to 372.30p, or 3.3 per cent, as it traded ex-dividend (without entitlement to the next dividend payment); GSK fell 55.00p to 1,735.50p and Lion Finance Group fell 460.00p to 12,370.00p, with no reason given for either. In the FTSE 250, Alliance News said Unite Group fell 5.1 per cent after a trading update, with analysts it cited pointing to falling property valuations.
Tesco results. Tesco’s interim results announcement, carried by Investegate on 8 October, covers the 26 weeks to 29 August 2026. Group sales excluding VAT and fuel were £33,776 million, up 1.6 per cent at constant exchange rates and 2.0 per cent at actual rates, and adjusted operating profit was £1,783 million, up 6.3 per cent at constant rates. Statutory profit before tax rose 11.5 per cent to £1,455 million. UK like-for-like sales (sales at stores open in both periods) rose 1.5 per cent over the half. Tesco now expects full-year adjusted operating profit of £3.15 billion to £3.30 billion, against the £3.0 billion to £3.3 billion range it gave in April, keeps its free cash flow guidance of £1.5 billion to £2.0 billion, raises its share buyback for the year to £950 million from £750 million, lifts capital expenditure guidance to about £1.7 billion from about £1.6 billion, and declares an interim dividend of 5.05p, up from 4.80p. Net debt was £10,037 million, or 2.0 times EBITDA (earnings before interest, tax, depreciation and amortisation). Why it matters: MT Newswires, via Yahoo Finance UK at 16:49 BST, quoted RBC Capital Markets as saying the first-half operating income was “ahead of consensus expectations”, and a larger buyback returns more cash to shareholders this year. Our 8 October edition covered the early reporting of the results; the figures above are from the company’s own announcement.
Imperial Brands buyback. In a trading update on 8 October, Imperial Brands said it is “On track to deliver full-year guidance for FY26 on all metrics”, with “Group adjusted operating profit growth is anticipated to be within our 3% to 5% range” and high-single-digit adjusted earnings per share growth. FY26 is the company’s financial year to 30 September 2026. It announced a £1.5 billion share buyback for FY27, the year to 30 September 2027, which it expects to complete no later than 29 October 2027. Our Investing Basics section explains how buybacks work.
Aberdeen sells half its Standard Life stake. Aberdeen Group’s result of secondary placing announcement on 8 October says it sold 52,000,000 Standard Life shares, about 5.2 per cent of the insurer’s issued share capital, at 839 pence each for gross proceeds of about £436 million, with settlement expected on 12 October; its remaining holding will be about 5.2 per cent. A placing is a sale of a block of shares to institutional investors. Against Alliance News’s Wednesday closing price of 871.50p (838.50p plus the 33.00p fall), the placing price was a discount of about 3.7 per cent. Aberdeen said it “intends to deploy the proceeds from the placing in accordance with its disciplined capital allocation policy”, and Daily Business reported chief executive Jason Windsor describing the sale as “further progress to simplify our group”. Standard Life was not a party to the placing and receives no proceeds. Aberdeen’s own shares closed up 1.37 per cent, according to MT Newswires.
Other UK items. The CMA said on 8 October that Brink’s has offered to sell NoteMachine and the UK business of TestLink to address competition concerns over its purchase of NCR Atleos, whose combined businesses operate more than half of UK cash machines; Elie Yoo, the CMA’s senior director of mergers, said “We will consult on these proposals before deciding whether they resolve our concerns”, according to the CMA’s statement. Separately, Daily Business reported on 8 October that German optics group Zeiss has acquired Ceres Holographics of Livingston, West Lothian, which develops holographic technology for car windscreen displays; the parties did not disclose the price.
US Market Update
According to Yahoo Finance, the S&P 500 closed Thursday at 7,765.36 (observed 16:46 EDT, 21:46 BST), down 36.41 points or 0.47 per cent from Wednesday’s 7,801.77. The Nasdaq Composite closed at 27,193.34 (Yahoo Finance, observed 17:15 EDT, 22:15 BST), down 345.35 points or 1.25 per cent from 27,538.69. The Dow Jones Industrial Average closed at 51,231.64 (Yahoo Finance, observed 16:00 EDT, 21:00 BST), up 51.77 points or 0.10 per cent from 51,179.87. In the week to Friday 2 October, the S&P 500 fell 0.27 per cent, the Nasdaq rose 0.45 per cent and the Dow fell 1.26 per cent (Yahoo Finance closes). Week to date, the S&P 500 is 0.55 per cent above its 2 October close of 7,722.72, the Nasdaq 0.01 per cent above 27,190.86 and the Dow 0.11 per cent above 51,176.96.
OpenAI revenue report hits chip stocks. TechCrunch reported at 11:19 am PDT (19:19 BST) on 8 October that the Financial Times had reported OpenAI telling investors its annualised revenue was “approaching $50 billion”, about $20 billion below the roughly $70 billion figure reported last month. Annualised revenue takes a recent month’s sales and multiplies them to a yearly rate. According to the FT as cited by TechCrunch, the higher figure came from “attempts by OpenAI’s own investors to produce a direct comparison with Anthropic’s annualised revenues”, because Anthropic counts sales made through cloud partners and OpenAI does not. TechCrunch said it had asked OpenAI for comment; its article carries no response. Yahoo Finance’s live blog said the Philadelphia Semiconductor Index fell as much as 4 per cent during the session, with Nvidia, Micron and Intel lower in afternoon trading, and CNBC reported that Oracle fell more than 5 per cent, Nvidia nearly 3 per cent and AMD almost 4 per cent, while Palantir rose 2 per cent after a Goldman Sachs upgrade. A StockTwits report carried by Yahoo Finance at 03:22 BST on 9 October said the iShares Semiconductor ETF fell 3.4 per cent in Thursday’s regular session, its worst day since 14 September, and that Nvidia, Oracle and CoreWeave edged higher in overnight trading; it quoted Futurum Group chief executive Daniel Newman saying “Broader reaction is overblown in my opinion”. Why it matters: OpenAI is a major customer of the chip and cloud companies whose shares fell, so investors treated its revenue figure as a read-across to their demand; the FT’s explanation, as reported, is a difference in accounting basis rather than a change in OpenAI’s business.
American Express penalty. The Federal Reserve Board announced at 4:30 pm EDT (21:30 BST) on 8 October an enforcement action against American Express Company for failing to sufficiently detect and report certain suspicious activity related to money laundering, citing “significant deficiencies in how American Express Company’s enterprise-wide anti-money laundering program was implemented”, particularly at its national bank subsidiary. It said the Office of the Comptroller of the Currency “has issued a separate enforcement action against the bank”. The OCC’s release says it issued a cease-and-desist order (an order requiring the bank to stop and fix the failings) and a $350 million civil money penalty against American Express National Bank, finding that it failed to identify, evaluate and sufficiently report in a timely way “approximately $13 billion of suspected trade-based money laundering activity that took place over the past decade”. Comptroller of the Currency Jonathan Gould said: “The OCC expects banks of American Express’s size and complexity to devote sufficient resources to ensure compliance” with anti-money-laundering laws. In a Form 8-K filing, reproduced by StockTitan, American Express said it consented to both orders and agreed to pay the $350 million, that “A portion of the civil money penalty was reserved for in prior periods”, that the penalty “does not impact the full-year 2026 guidance” and that “The consent orders do not impose an asset cap on the Company”. Why it matters: the orders require the company to fix its controls but, by its own account, do not restrict its growth or change its 2026 guidance.
PepsiCo results. PepsiCo reported on 8 October third-quarter net revenue of $25.27 billion, up 5.6 per cent, with organic revenue (sales growth excluding currency moves, acquisitions and disposals) up 3.1 per cent and operating profit up 19 per cent to $4.26 billion for the quarter ended 5 September. Earnings per share rose 17 per cent to $2.23, and core earnings per share, the company’s adjusted measure, rose 2 per cent to $2.34. Its 2026 guidance is for net revenue growth of about 6 per cent and core earnings per share growth of 2.5 to 3.5 per cent. According to Yahoo Finance, the shares closed at $128.34 on 8 October, up 3.7 per cent from $123.73 on 7 October. Why it matters: PepsiCo is one of the largest US consumer goods companies, so its sales growth and guidance are a read on household demand that the technology-led Nasdaq fall does not give.
Waller on further rate rises. Fed Governor Christopher Waller said in a speech at the Istanbul Economic Forum on 8 October: “Overall, the new data reinforce my view that the labor market is stable and inflation is too high.” He added: “I anticipate additional hikes to support a timelier return of inflation to our 2 percent goal”, and “The hikes do not need to come at consecutive meetings, but they should be in place in an acceptable period of time.” He described the Summary of Economic Projections, the quarterly chart of individual policymakers’ forecasts, as a signalling tool, noting that 16 of the 18 participants in September expected at least one more rise this year. The federal funds target range is 3.75 to 4.00 per cent, after a quarter-point rise on 16 September by a 12 to 0 vote, according to the Fed’s statement; the minutes of that meeting were covered in our 8 October edition. Waller’s remarks are one governor’s view, not a committee decision.
Jobless claims. The US Department of Labor said at 8:30 am EDT (13:30 BST) on 8 October that seasonally adjusted initial jobless claims (new applications for unemployment benefit) were 197,000 in the week ending 3 October, down 2,000 from the previous week, whose figure was revised up by 2,000 to 199,000. The four-week moving average was 198,000, down 2,500. Why it matters: the weekly claims count is the most timely official measure of lay-offs, and a figure below 200,000 fits Waller’s description of a stable labour market.
Global Markets
DPA, via Yahoo Finance at 19:03 BST on 8 October, reported: “European stocks closed lower on Thursday, with several markets falling to multi-month lows as rising oil prices, higher bond yields and concerns over inflation and interest rates weighed on investor sentiment.” It put the STOXX 600 down 0.75 per cent, the DAX down 1.18 per cent and the CAC 40 down 0.51 per cent, with Volkswagen, Infineon and Porsche among Frankfurt’s fallers and TotalEnergies up nearly 3 per cent in Paris. Alliance News’s closing report, cited in the UK section, also put the DAX down 1.2 per cent and the CAC 40 down 0.5 per cent.
ECB accounts. The European Central Bank published the account of its 9 to 10 September meeting at 13:30 CET (12:30 BST) on 8 October. It says “all members supported the proposal made by Mr Lane to raise the three key ECB interest rates by 25 basis points”, taking the deposit facility rate to 2.50 per cent, and that members judged “the risks to the inflation outlook were to the upside”, mainly because of the Middle East conflict and Russia’s war against Ukraine. The account records euro-area inflation of 3.3 per cent in August, with energy inflation of 14.3 per cent. The ECB’s meeting calendar lists the next monetary policy meeting on 28 to 29 October in Frankfurt.
Asia. The Nikkei 225 closed Thursday at 69,042.11, down 1.42 per cent from 70,035.71, according to Yahoo Finance; at 12:49 JST (04:49 BST) on Friday it was 68,668.35, down 0.54 per cent, with the market open. The Hang Seng closed Thursday at 23,785.79, down 1.43 per cent from 24,130.50, and at 11:50 HKT (04:50 BST) on Friday was 24,041.59, up 1.08 per cent, with the market open, per Yahoo Finance. These Friday figures are mid-session, not closes.
Bonds, Currencies and Commodities
Gilts. Reuters, via Investing.com in a report updated at 10:55 on 8 October, said “British long-term borrowing costs hit fresh multi-decade highs on Thursday as part of a global bond selloff”, with the 10-year gilt yield at 5.527 per cent, up more than 7 basis points on the day and the highest since July 2007, and the 30-year at 6.05 per cent, up around 7 basis points and the highest since early 1998. By the end of the day the move had partly reversed. Trading Economics puts the 10-year yield at 5.49 per cent for 8 October, up 0.05 percentage points on the day (date only, no time given); Investing.com’s daily table puts the 30-year at 5.938 per cent for 8 October, down from 5.979 per cent on 7 October after a high of 6.047 per cent (date only, no time given). Providers differ on the 10-year close: Investing.com’s daily table shows 5.427 per cent for 8 October. Why it matters: the 10-year yield is the benchmark for the government’s new borrowing costs ahead of the 28 October Budget. HM Treasury’s minutes of Chancellor John Healey’s 6 October meeting with gilt-edged market makers, published on 7 October, say he stressed “fiscal credibility in a challenging global economic environment” and reaffirmed the government’s commitment to its fiscal rules. Bank Rate is 3.75 per cent: the Monetary Policy Committee held it there on 17 September by six votes to three, with Megan Greene, Catherine Mann and Huw Pill preferring a rise to 4 per cent, according to the Bank’s minutes.
US Treasuries. The 10-year Treasury yield ended Thursday at 5.231 per cent, according to Yahoo Finance (observed 14:59 EDT, 19:59 BST), down 4.6 basis points from Wednesday’s 5.277 per cent. The Treasury’s $22 billion 30-year bond reopening, flagged in our 8 October edition, drew a high yield of 5.618 per cent, the highest since August 2000 and 31 basis points above the 5.308 per cent of the 10 September auction, according to TFTC’s auction tracker, which cites TreasuryDirect’s results. The bid-to-cover ratio (bids received divided by the amount sold) was 2.54, against an average of 2.41 over the previous six auctions; indirect bidders, a group that includes foreign central banks, took 72.3 per cent, direct bidders 20.9 per cent and primary dealers 6.8 per cent. Yahoo Finance’s live blog said the 30-year yield reached 5.61 per cent; the US Treasury’s daily par yield curve puts the 30-year at 5.60 per cent for 8 October, down from 5.67 per cent on 7 October.
Currencies. Sterling closed at $1.3229 on 8 October, up from $1.3213 on 7 October, and the euro at $1.1215, up from $1.1201 (Yahoo Finance 17:00 New York rates). At 04:59 BST on 9 October sterling was $1.3241 and the euro $1.1230, per Yahoo Finance.
Oil. Brent crude futures closed at $104.28 a barrel on 8 October, up $4.08 or 4.07 per cent from $100.20, and WTI closed at $91.49, up $3.21 or 3.64 per cent from $88.28, according to Yahoo Finance (WTI quote page). At 04:50 BST on 9 October Brent was $102.82 and WTI $90.41. Oilprice.com reported at 5:46 am CDT (11:46 BST) that Brent was $105.02, up 4.81 per cent from Wednesday’s close, citing a Reuters report that a US Navy-led information outlet counted a dozen attacks on tankers between 28 September and 2 October, and Kpler data showing tanker traffic through the strait at its lowest since late July. Alliance News quoted Brent at $105.57 on Thursday against $101.77 late on Wednesday. Prices eased later: CBS News’s live coverage recorded at 12:45 pm ET (17:45 BST) that President Trump posted on Truth Social that “we will not be attacking Iran at any time prior to the Midterm Elections to be held in the United States on November 3rd”, while saying the US blockade of Iranian ports “will remain in full force and effect”. CBS said The Atlantic had reported that the White House asked the Pentagon to prepare strike options, and that Iran’s foreign minister said Tehran was reviewing the US reply to its “seven-day plan”. For background, CBS says US and Israeli attacks on Iran began on 28 February 2026. Yahoo Finance’s live blog said oil trimmed its gains after the post.
Metals. COMEX gold futures closed at $4,157.00 an ounce on 8 October, up from $4,140.70, and were $4,200.60 at 04:50 BST on 9 October (Yahoo Finance). COMEX copper closed at $6.519 a pound, down 1.17 per cent from $6.5965 (Yahoo Finance).
Crypto
Bitcoin was $82,360 at 04:59 BST on 9 October, down 0.44 per cent over 24 hours, with a 24-hour range of $80,427 to $83,215, according to CoinGecko. Ether was $2,491.69 (down 2.83 per cent), Solana $110.36 (down 4.61 per cent), XRP $1.39 (down 1.47 per cent) and Chainlink $12.84 (down 2.55 per cent). These five assets are a selection, not the whole market.
CRYPTO MARKET PICTURE · FIXED SNAPSHOT
Five crypto assets, one clear view
| Asset | USD price | 24h change | Magnitude (0 to 5 per cent) |
|---|---|---|---|
| BTC Bitcoin |
$82,360.00 | -0.44 per cent | |
| ETH Ethereum |
$2,491.69 | -2.83 per cent | |
| SOL Solana |
$110.36 | -4.61 per cent | |
| XRP XRP |
$1.39 | -1.47 per cent | |
| LINK Chainlink |
$12.84 | -2.55 per cent |
Powered by CoinGecko. Retrieved 9 Oct 2026, 05:00 BST. Provider observation times: BTC 9 Oct 2026, 04:59 BST; ETH 9 Oct 2026, 04:59 BST; SOL 9 Oct 2026, 04:59 BST; XRP 9 Oct 2026, 04:59 BST; LINK 9 Oct 2026, 04:59 BST. Bars compare the size of changes on a shared 0 to 5 per cent scale, not prices or capitalisation. Signs show direction. This selected crypto sample is not a picture of all crypto assets or wider financial markets; these archived quotes do not update.
ETF outflows. CoinDesk reported at 7:15 am EDT (12:15 BST) on 8 October that US spot bitcoin exchange-traded funds recorded net outflows of $487.1 million on Wednesday 7 October, the largest since 25 June, citing SoSoValue, leaving October to date at a net outflow of $165.6 million after about $2.65 billion of inflows in September. Cointelegraph, citing Farside Investors, put Wednesday’s figure at $484.9 million, led by BlackRock’s IBIT ($207.7 million) and Fidelity’s FBTC ($105.1 million), and said US spot ether ETFs lost $160.9 million, a seventh straight session of outflows, with about $569 million leaving since 29 September. Cointelegraph said bitcoin traded near $82,700 on Thursday, down about 2 per cent over 24 hours, citing CoinGecko; Yahoo Finance put it at $82,347.48 at 7:11 am ET (12:11 BST), linking the fall to inflation concerns as oil prices rose. Why it matters: spot ETF flows are one of the few daily measures of institutional demand for bitcoin, and a week of outflows from ether funds removes a source of buying that supported prices in September. Our Crypto Decoded guides explain how spot crypto ETFs hold and value their assets.
AI, Technology and Investor Tools
Anthropic’s Haiku 5.5. Anthropic’s newsroom lists “Introducing Claude Haiku 5.5” on 7 October, describing it as “Our fastest, cheapest, and most capable small model yet.” The company’s Haiku product page prices it at “$0.10 per million input tokens and $0.50 per million output tokens” for prompts up to 100,000 tokens, with $0.50 and $2.50 for longer prompts, and says it is available on Claude.ai for Free, Pro, Max, Team and Enterprise users, on the Claude Platform, Amazon Web Services, Google Cloud and Microsoft Foundry, and in Claude Code. SiliconANGLE reported that Anthropic quotes a “75% average saving” against Haiku 4.5, a company claim, and that Sonnet 5.5 cache-read prices were halved to 10 cents per million tokens. A token is a fragment of text, roughly three quarters of a word.
OpenAI’s revenue basis. As set out in the US section, the FT’s reporting, as relayed by TechCrunch, turns on how annualised revenue is counted: whether sales made through cloud partners are included. For readers comparing private AI companies, the lesson is that “annualised revenue” figures reported for private firms are not audited and may not be on the same basis from one company to the next.
Trading tools. Securitize’s tokenised shares, Standard Chartered’s custody plans and other crypto-infrastructure items in this morning’s feeds were available only as headlines by the cut-off and are not covered here.
What to Watch Next
- Friday 9 October: University of Michigan preliminary October consumer sentiment, 10:00 am EDT (15:00 BST). CMA invitation to comment on BT/TalkTalk closes.
- Monday 12 October: Pennon shares marked ex-rights at 8:00 am, per the rights issue terms covered on 8 October; settlement of Aberdeen’s Standard Life placing expected; US Columbus Day holiday.
- Tuesday 13 October: Fed Governor Waller in a discussion on AI at the Bloomberg New Economy Forum, New Delhi, 3:45 am EDT (08:45 BST), per the Fed calendar.
- Wednesday 14 October: US consumer price index for September, 8:30 am EDT (13:30 BST), per the BLS schedule. Fed Beige Book, 2:00 pm EDT (19:00 BST), per the Fed calendar.
- Thursday 15 October: ONS GDP monthly estimate for August, 7:00 am BST. Fed Chair Kevin Warsh in a fireside chat with IMF Managing Director Kristalina Georgieva in Bangkok, 11:30 pm EDT (04:30 BST on 16 October), per the Fed calendar.
- Friday 16 October: Fed industrial production and capacity utilisation, 9:15 am EDT (14:15 BST).
- Monday 19 October: CMA report on BT/TalkTalk due to the Secretary of State by 5pm.
- Tuesday 20 October: ONS labour market overview, 7:00 am BST.
- Wednesday 21 October: ONS consumer price inflation for September, 7:00 am BST, and public sector finances, 7:00 am BST.
- Friday 23 October: ONS retail sales for September, 7:00 am BST.
- Monday 26 October: Pennon rights issue acceptance and payment deadline, 11:00 am; result due by 8:00 am on 27 October.
- Tuesday 27 to Wednesday 28 October: Federal Open Market Committee meeting; statement at 2:00 pm EDT (18:00 GMT) and press conference at 2:30 pm EDT (18:30 GMT) on 28 October, per the Fed calendar. The UK Budget is also on 28 October, according to Reuters; no time has been published.
- Thursday 29 October: ECB monetary policy decision and press conference, Frankfurt; the ECB calendar gives no times.
- Tuesday 10 November: US consumer price index for October, 8:30 am EST (13:30 GMT), per the BLS schedule.
Limitations: Sharecast’s London closing report, CNBC’s market pages and several of The Defiant’s articles could not be read in full before the cut-off; closing movers are therefore taken from Alliance News and MT Newswires, and crypto items that were available only as headlines have been left out.
Explore the live Bitcoin chart and Fear & Greed indicator
Optional live context
The briefing above is a fixed, dated snapshot. These provider displays update independently and may show different values. They do not change the article’s archived figures.
Bitcoin chart: daily candles, US dollars
TradingView · Bitstamp BTC/USD · London timezone. Each candle shows one day’s opening, high, low and latest or closing price. The latest candle is still forming. This is one exchange, not CoinGecko’s aggregated quote. Check the provider’s displayed time and data status.
The chart loads separately and may take a moment to appear. If it stays blank or looks stale, use the source-chart link below or hide the chart area. The dated market table remains readable without it.
Open the Bitcoin source chart on TradingView ↗
Latest provider Fear & Greed indicator
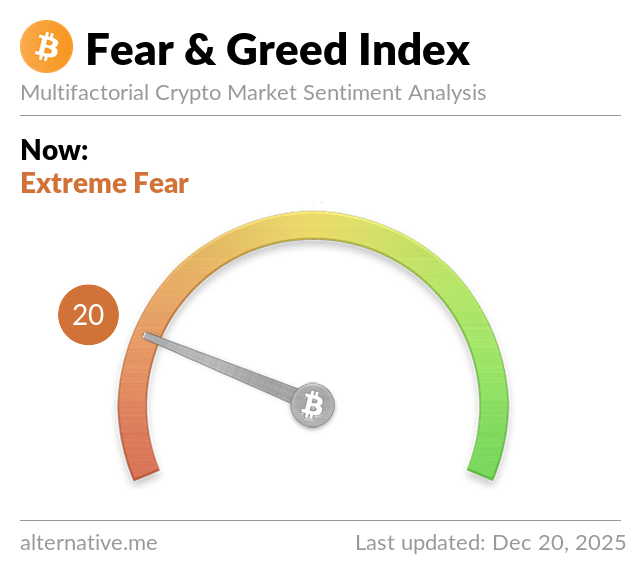
Sentiment image unavailable. Use the provider link above; the dated reading in the article remains available.