Bed and ISA explained: costs, tax and a worked example
Bed and ISA explained for UK investors: how selling and rebuying works, the costs and tax to check, and a worked example before moving your investments.
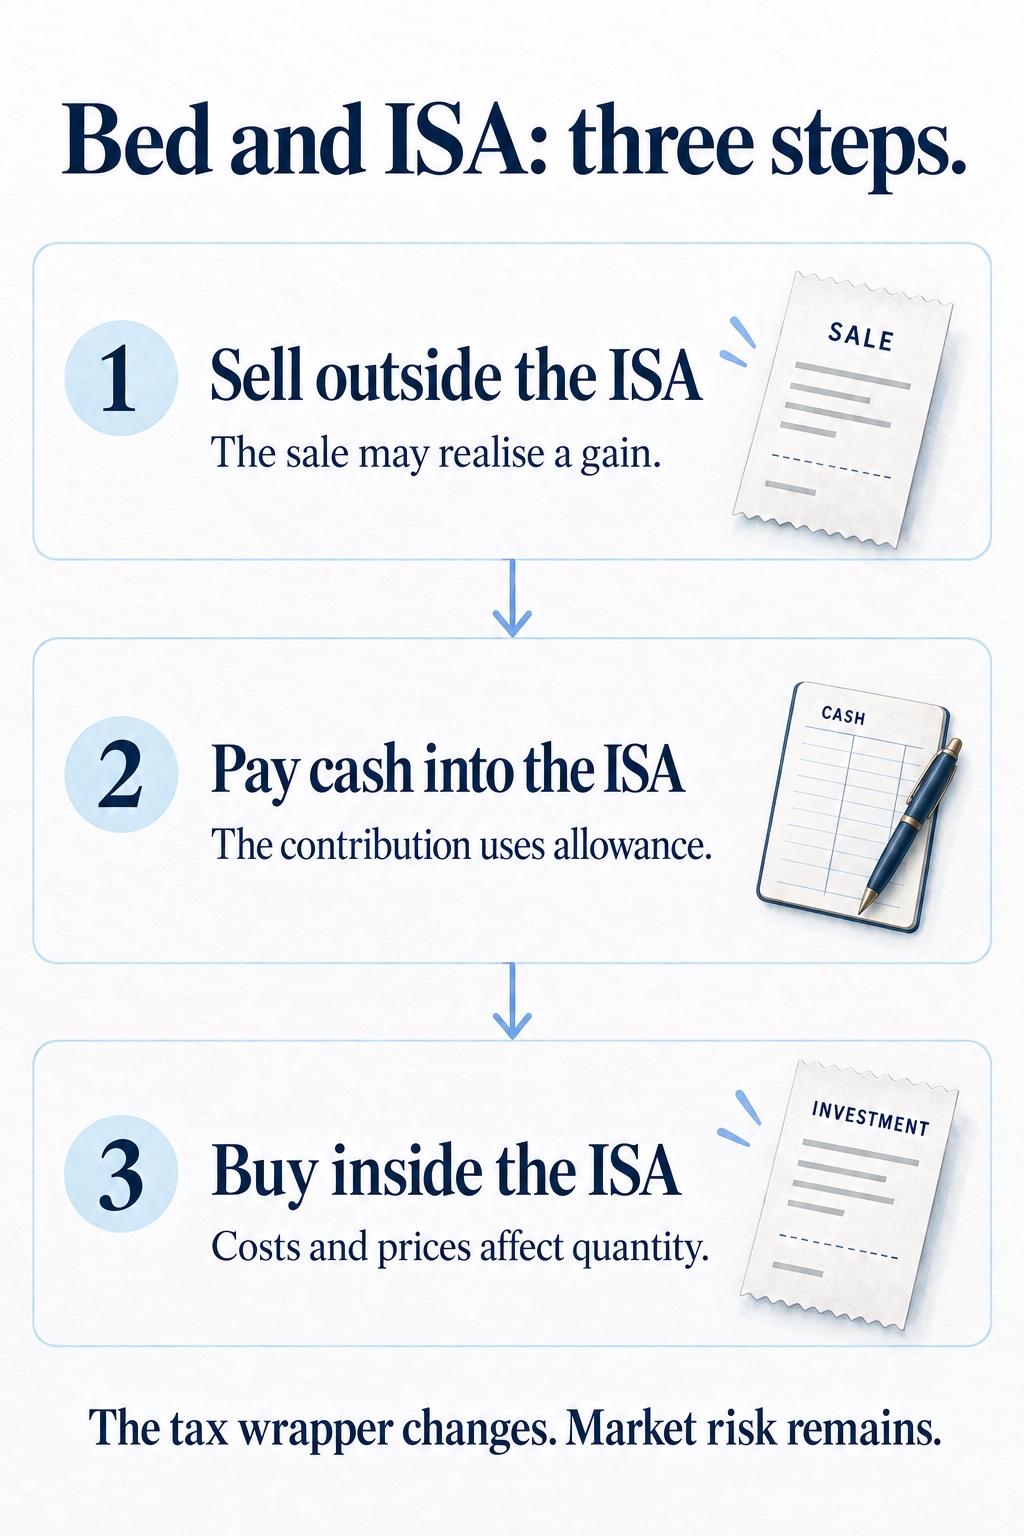
You own an investment outside an ISA and would prefer future returns to sit inside one. A Bed and ISA can make that change, but it is a sale and a new purchase, not a tax-free relabelling of what you already own.
A Bed and ISA means selling investments in a taxable account, paying cash into a Stocks and Shares Individual Savings Account, then buying investments inside it. You can often repurchase the same holding. The useful question is not simply whether an ISA shelters returns, but what the move will cost and what happens to the gain you have already made.
The short version
- The sale outside the ISA can realise a taxable gain. Moving the proceeds does not erase it.
- The cash paid into the ISA uses subscription allowance, not just the profit from the sale.
- Charges, the difference between buying and selling prices, and market movements can leave you with fewer shares.
- An existing ISA moving between providers is a different process. Ask for an ISA transfer.
What actually moves into the ISA?
Think of two accounts with a sale between them. Your general investment account, often shortened to GIA, holds investments outside an ISA or pension. You sell there, then subscribe cash to the ISA and buy there. A provider may combine those steps into one instruction, but the underlying transactions still happen.
GOV.UK explains that existing non-ISA shares cannot normally be transferred straight into an ISA. Certain employee share-scheme shares are an exception; check the scheme rules before selling those unnecessarily. The new purchase must also be an investment your chosen ISA can hold.
If the investment is already inside an ISA, do not confuse this with changing ISA providers. Use the receiving provider’s formal ISA transfer process. Withdrawing to your bank and paying into a new account yourself can lose the transfer protection. A Bed and ISA starts outside the wrapper.
Check the allowance and the gain separately
For the 2026/27 tax year, running from 6 April 2026 to 5 April 2027, the overall adult ISA subscription allowance is £20,000. This is shared across your ISAs, not a fresh £20,000 for each provider. Check the current ISA rules and how much you have already contributed elsewhere.
For example, £8,000 already paid into a Cash ISA would leave £12,000 for new subscriptions that year, assuming no other subscriptions or special replacement rights. If your holding is larger, moving only part may be possible. Do not assume your broker knows about accounts elsewhere.
The gain is a different calculation. For an ordinary share sale, it is generally sale proceeds less the allowable acquisition cost and selling costs, subject to the relevant tax rules. HMRC’s guidance on calculating a share gain explains deductible costs and special cases.
The standard individual Capital Gains Tax annual exempt amount is currently £3,000. That concerns overall gains, with losses and other circumstances affecting the calculation. It is not an amount you can deduct from every sale, nor is it the amount you can pay into an ISA. Keep enough money available for any tax due.
If you acquired the holding at different prices, do not automatically use the profit number on your app. Our guide to average purchase price and UK tax records explains why a platform’s average and the allowable tax cost can differ.
A worked example: one move, three different numbers
Suppose Sam owns 1,000 shares in a fictional UK company outside an ISA. Their total allowable acquisition cost is £7,000, including original buying costs. Assume no share-matching complications and enough unused ISA allowance. These are hypothetical prices and charges, not a broker quotation or a recommendation.
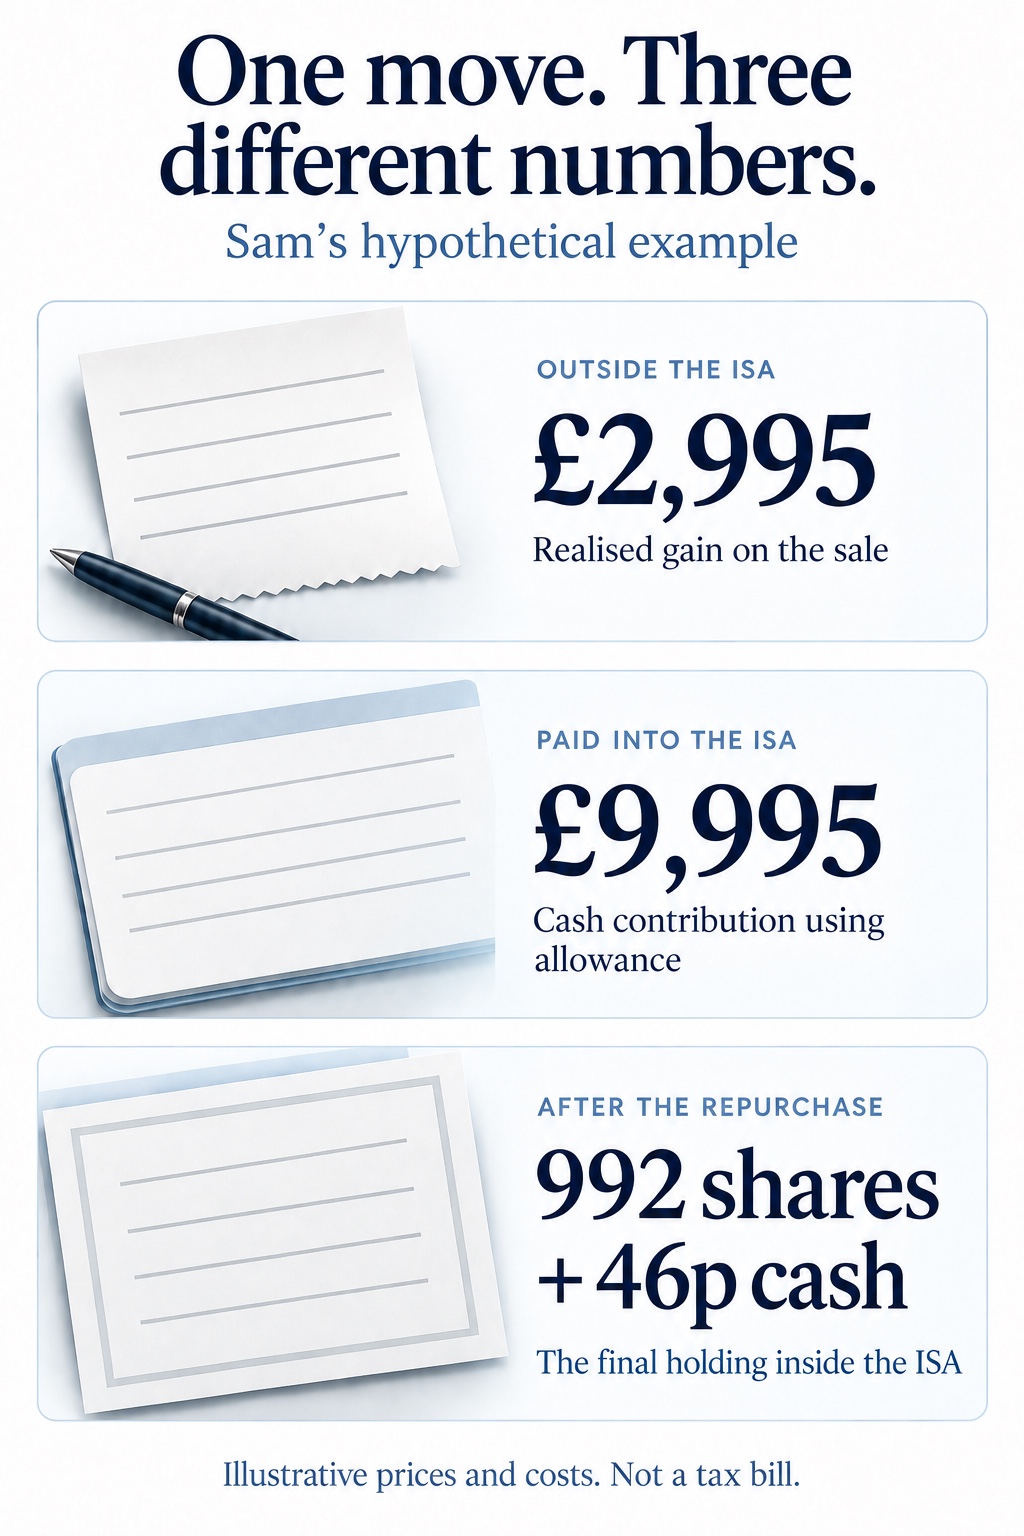
Sam sells all 1,000 shares at £10 each. Gross proceeds are £10,000. After a £5 selling charge, the cash available is £9,995. The realised gain is £10,000 minus £5 minus £7,000: £2,995. Any tax outcome depends on Sam’s wider position, not just this transaction.
Sam pays the £9,995 into the ISA. That uses £9,995 of subscription allowance, not £2,995. The gain arose in the taxable account; paying in the proceeds does not cancel it.
Now suppose the purchase price is £10.02 per share. The example assumes a £5 buying charge and that 0.5% Stamp Duty Reserve Tax applies to this purchase. Only whole shares are available.
| Item | Calculation | Amount |
|---|---|---|
| 992 shares | 992 × £10.02 | £9,939.84 |
| Purchase tax | 0.5%, rounded to pennies | £49.70 |
| Buying charge | Illustrative fixed fee | £5.00 |
| Total spent | Shares + tax + charge | £9,994.54 |
| Cash remaining | £9,995 − £9,994.54 | £0.46 |
Sam now has 992 shares and 46p cash inside the ISA, rather than 1,000 shares outside it. The number fell because of the assumed transaction costs and higher purchase price. That is not proof the move was worthwhile or a mistake: it is the immediate cost to weigh against the potential future tax benefit. Ongoing account charges and any Capital Gains Tax payment are excluded from the repurchase table.
The costs and timing to ask about
A zero selling commission does not necessarily mean a cost-free move. Ask about buying charges, currency conversion, the bid-offer spread (the gap between the price available to sell and the price to buy), and any tax on the purchase. Market prices may also move between the two trades.
Buying inside an ISA does not generally remove purchase taxes. GOV.UK sets out when Stamp Duty or Stamp Duty Reserve Tax applies, including exemptions. The 0.5% in Sam’s example is an explicit assumption for those shares, not a charge that applies to every fund or investment.
Timing depends on the holding and service. For example, Hargreaves Lansdown describes an almost immediate repurchase once its Share Exchange trades are executed, but says processing the instruction can take up to four working days. Its fund route works differently and waits for settlement, when the sale’s cash becomes available. This illustrates a distinction to check, not a provider recommendation or a universal timetable.
Ask how your provider limits time out of the market, what happens if one part cannot complete, and whether its tax-year deadline is earlier than 5 April. Do not assume an instruction submitted on the final day will complete in time.
Do you have to wait 30 days to buy back?
A repurchase inside an ISA is treated differently from buying back into a taxable account for share-matching purposes. Fidelity’s technical guidance explicitly confirms that funds sold from its Investment Account can be repurchased inside an ISA without the 30-day rule applying. Do not impose a 30-day wait simply because you have heard the phrase “bed and breakfasting”. This does not mean the platform can execute instantly.
Other purchases outside the ISA can affect your gain calculation. If you are trading the same holding elsewhere or have complicated acquisition records, check the matching rules or get tax advice before relying on a simple example.
Before you give the instruction
- Check the investment. Would you still want to own it? A different account does not improve a weak holding or remove market risk.
- Check the room. Add up this tax year’s ISA subscriptions across providers and confirm what the proposed contribution will use.
- Check the sale. Establish the allowable cost, likely gain or loss and any reporting or payment obligations.
- Check the mechanics. Confirm eligible investments, all charges, likely timing and whether the same quantity can be repurchased.
- Check the result. Keep both contract notes, the ISA contribution record and any cash balance. Reconcile what was sold with what was bought.
The useful outcome is an investment you still want, held in an appropriate account, with the costs and tax consequences understood. The ISA changes how future returns are treated. It does not rewrite the history of the holding you sold.
This article provides general financial education, not personal investment or tax advice. Investments can fall in value and you may get back less than you invest. Tax rules can change and their effect depends on your circumstances. Seek qualified advice if you are unsure how they apply to you.