Market Daily: China’s factories return to expansion as US yields stay above 5%
China’s manufacturing PMI returns to expansion, US yields remain above 5%, Bitget reports restored ETH withdrawals and crypto fraud complaints expose investor risks.
MARKET DAILY · MARKETS, TECHNOLOGY AND CRYPTO · 2026-09-30
Digitally generated conceptual header, not a real event or a forecast. News cut-off 30 Sept 2026, 06:10 BST; sources checked through 30 Sept 2026, 06:17 BST; the fixed crypto observations are timed separately below.
Correction note: An earlier version incorrectly said no suitable UK company announcement was available before this briefing’s news cut-off. See the UK Market Update and the correction note below.
The day ahead
China’s official manufacturing survey moved narrowly back into expansion in September, while a benchmark US government-bond yield above 5%, a 16-month dollar high against the euro and Brent crude above US$100 a barrel remain important tests for markets. In cryptocurrency, Bitget says Ethereum withdrawals resumed after its US$387.5 million security incident, while two US regulatory complaints allege that investors lost at least US$15.3 million through fictitious crypto and artificial-intelligence trading schemes.
The evidence does not point in one direction. China’s headline factory reading crossed the expansion threshold, but employment and the readings for medium-sized and smaller manufacturers remained below 50. Oil fell during Tuesday’s completed session but remained expensive in absolute terms, while high government-bond yields continued to raise the return against which investors compare shares and other risky assets.
News selection closed at 06:10:24 British Summer Time, or 05:10:24 UTC, on Wednesday 30 September 2026. This preceded the London cash-equity opening and many scheduled 07:00 BST UK company announcements. The fixed cryptocurrency observations were made separately at 06:08:30 BST.
UK Market Update
Vesuvius weighs a possible cash-and-share offer
London-listed Vesuvius said at 08:30 BST on Tuesday 29 September that it was evaluating a non-binding cash-and-share proposal from RHI Magnesita. The terms were 470p in cash plus 0.028 RHI shares for each Vesuvius share, valued by Vesuvius at 551p per share using RHI’s one-month average share price to 27 August. Its board had not recommended a bid; no firm offer or completed takeover existed. RHI must announce a firm intention to bid or say it will not proceed by 5pm London time on 27 October. Vesuvius’s 29 September announcement sets out the proposal and deadline.
The FTSE 100 closed Tuesday at 10,636.71, down about 0.5%, while the FTSE 250 rose 0.2%, according to Alliance News reporting carried by MarketScreener. These were completed Tuesday results, not indications for Wednesday’s still-unopened London cash market.
For UK investors, higher international borrowing costs and expensive dollar-priced energy remain relevant to financing and margins. Companies with frequent refinancing needs, long-dated profit expectations or little room to pass on costs may be more sensitive, though that does not predict an individual share’s direction.
US Market Update
US shares slip as Treasury yields stay high
US shares ended Tuesday 29 September modestly lower: the S&P 500 fell 0.2%, the Dow 0.3% and the Nasdaq 0.1%, according to AP’s completed-session report. The benchmark 10-year Treasury yield ended around 5.25% after touching a higher intraday level. Higher government yields can raise borrowing costs and the return investors demand from shares, although they do not explain every company’s move.
The dollar index, which measures the US currency against a basket including the euro and yen, rose 0.2% to 101.40 during Tuesday’s completed trading and reached its highest level since 28 July, according to Reuters. The figure is an index level rather than an exchange rate against one currency.
Michael Barr separates current AI spending from future productivity
Federal Reserve Governor Michael Barr said on 29 September that inflation remained too high. He noted that the Federal Open Market Committee had raised short-term rates earlier in the month and said that, in his own base case, further policy adjustments were likely to be needed to bring inflation down. This was one governor’s assessment, not a new committee decision or a pre-announced future rate rise.
Barr said the near-term AI build-out was boosting economic activity and pushing up prices for computer chips and related equipment. Over a longer period, successful adoption could allow wages and economic activity to grow more quickly without producing the same inflation pressure. He said it remained too early to know whether those longer-term dynamics were operating.
The distinction is useful for company analysis. Spending on chips, data centres, software and implementation can be measured now. Broad productivity gains, future revenue and lower costs remain prospective until results demonstrate them.
Global Markets
China’s manufacturing PMI moves just above 50
China’s manufacturing purchasing managers’ index, or PMI, rose from 49.8 in August to 50.1 in September, according to the National Bureau of Statistics release published at 09:30 China time on 30 September. A PMI above 50 indicates expansion compared with the previous month. It does not mean factory output grew by 50.1%.
The production index reached 51.7 and new orders registered 50.5. The employment index was weaker at 48.4. Large-company PMI was 50.6, while the medium-sized and small-company readings were 49.7 and 48.9 respectively. The return to expansion was therefore uneven rather than comprehensive.
For investors in exporters, miners and industrial companies, the next test is whether the improvement extends to sustained orders, employment and smaller manufacturers. One reading only slightly above 50 is evidence of stabilisation, not proof of a strong recovery.
India illustrates the pressure on an energy importer
The Indian rupee weakened to 96.1450 per US dollar during trading on Tuesday 29 September, down nearly 0.2% on the day and at a two-month low, according to Reuters reporting reproduced by MarketScreener. The quote means one US dollar bought 96.1450 rupees.
Reuters reported that foreign investors had withdrawn US$3.7 billion from Indian markets during September. India is a large net energy importer, so expensive dollar-priced oil can increase demand for foreign currency and raise import costs. That mechanism does not prove that oil alone caused the entire currency move.
Bonds, Currencies and Commodities
The dollar reaches a 16-month high against the euro
The euro touched US$1.1312 during Tuesday trading, its lowest value against the dollar since May 2025, before standing at US$1.1341, down 0.26% on the day in the Reuters report. These figures are US dollars per euro, so a lower number means the euro buys fewer dollars.
Currency movements can change a UK investor’s sterling return independently of the local performance of an overseas asset. A strong dollar can also raise costs for businesses purchasing dollar-priced fuel, commodities or components.
November Brent settles at US$102.59 a barrel
November Brent crude futures settled at US$102.59 per barrel on Tuesday 29 September, down 2.56% in the completed session. Reuters also reported that Saudi Arabia had resumed oil loading from Yanbu after restarting the East-West Pipeline, improving one export route. Neither that logistics development nor any other single event establishes the full cause of the price move.
The settlement provides a cleaner follow-up to the previous edition’s intraday observation of US$106.99 for the same delivery month. A settlement is an end-of-session reference, while an intraday quote records a price during open trading. Matching the delivery month avoids comparing different futures contracts as though they were identical.
Spot gold recovers from Monday’s low
Spot gold stood at US$4,143.87 per troy ounce at 07:08 GMT on Tuesday 29 September while trading was open, up 0.7%, according to Reuters reporting reproduced by MarketScreener. US gold futures were separately quoted at US$4,175.10, up 0.2%. Spot metal and futures are different instruments.
Higher bond yields can make a non-interest-paying asset less attractive at the margin, while geopolitical risk can support demand for perceived defensive assets. These forces can operate simultaneously and should not be treated as proof of one simple cause for a daily move.
Crypto
The selected fixed sample was mixed during continuous trading
The panel below is an archived snapshot of five selected crypto assets quoted in US dollars. Provider observations were made at 05:08:30 UTC, or 06:08:30 BST, on 30 September while crypto markets were trading continuously. It is a crypto-only sample, not a representation of all digital assets or wider financial markets.
Five crypto assets, one clear view
| Asset | USD price | 24h change | Magnitude (0–3%) |
|---|---|---|---|
| BTC Bitcoin |
$83,249.00 | +0.09% | |
| ETH Ethereum |
$2,669.75 | +0.18% | |
| SOL Solana |
$118.69 | +0.94% | |
| XRP XRP |
$1.50 | +0.88% | |
| LINK Chainlink |
$14.38 | -2.59% |
Powered by CoinGecko. Retrieved 30 Sept 2026, 06:10 BST. Provider observation times: BTC 30 Sept 2026, 06:08 BST; ETH 30 Sept 2026, 06:08 BST; SOL 30 Sept 2026, 06:08 BST; XRP 30 Sept 2026, 06:08 BST; LINK 30 Sept 2026, 06:08 BST. Bars compare the size of changes on a shared 0–3% scale, not prices or capitalisation. Signs show direction. This selected crypto sample is not a picture of all crypto assets or wider financial markets; these archived quotes do not update.
Bitcoin was US$83,249 with a rolling 24-hour change of approximately 0.09%. Ethereum was US$2,669.75, up approximately 0.18%; XRP was US$1.50, up approximately 0.88%; and Solana was US$118.69, up approximately 0.94%. Chainlink fell approximately 2.59% to US$14.38. These were continuously updating provider observations rather than formal daily closes, and the sample does not establish why any asset moved.
Bitget says Ethereum withdrawals resumed
Bitget’s dated ETH-specific notice says Ethereum withdrawals resumed on 29 September on Ethereum, BSC, Arbitrum One, BASE and Optimism, after BTC withdrawals resumed on 28 September. The exchange’s incident page reports an estimated impact of US$387.5 million in its 25 September timeline entry.
These are operator statements, not independent assurance that every customer can withdraw, or of the exchange’s reserves or financial condition. Users should check the exact asset and network shown in their account before transferring funds.
The same page scheduled USDT withdrawal restoration for 08:00 UTC on 30 September, after this briefing’s cut-off, and other coins, fiat and peer-to-peer services for 08:00 UTC on 2 October. Those remain scheduled actions until a fresh status notice confirms completion.
Cristoniq’s first-transfer runbook explains how to match the asset, network and destination, send a small test and confirm arrival before moving a larger amount.
Aave proposal would give Sentora day-to-day risk responsibility
Sentora has proposed externally curated lending markets on Aave V4. Under the public governance proposal, Aave’s decentralised autonomous organisation, or DAO, would retain ownership of the contracts and administrative roles, while Sentora would select collateral, risk parameters, interest-rate curves and price oracles.
Risk-increasing changes would face a 48-hour on-chain delay, while the proposed markets’ protocol revenue would be split equally between the Aave DAO and Sentora. Aave’s usual risk-service providers would not be responsible for monitoring the instance. This remains a proposal seeking feedback, not an approved deployment.
SEC complaints allege fictitious AI and crypto trading schemes
US Securities and Exchange Commission complaints allege that Cryptoaiml and TSAI took at least US$12.5 million and US$2.8 million respectively from investors through schemes involving social media, false regulatory claims and fictitious trading systems. The allegations were reported on 29 September by WealthManagement.com, which described and quoted the filed complaints.
The report says Cryptoaiml allegedly displayed fictitious account profits and demanded advance fees when investors tried to withdraw. TSAI allegedly claimed that customer funds would rent AI trading bots, although the complaint says no such bots existed. These are allegations seeking court remedies, not adjudicated findings.
A Form D filing is not evidence that an investment has SEC approval. Investors can check the named legal entity and claimed regulatory status against public records. Guaranteed returns, recruitment rewards and demands for additional withdrawal fees are warning signs, while a balance displayed on a private dashboard is not proof that assets or trades exist.
AI, Technology and Investor Tools
A two-stage test for AI investment claims
Governor Barr’s 29 September speech provides a practical framework for evaluating AI-related companies. Near-term investment can increase economic activity and demand for scarce equipment. Productivity improvements may arrive later because companies must install technology, reorganise processes and train staff before benefits become widespread.
A practical AI research workflow
- Record completed facts such as capital expenditure, disclosed revenue, signed customers and measurable cost changes.
- Separate prospective claims such as future productivity, market share, pricing and promised integrations.
- Check whether the company reports economic results as well as demonstrations, registrations or usage.
- Compare spending with operating cash flow and margins over consistent reporting periods.
- Keep each figure’s source, currency, reporting period and calculation assumptions beside it.
Barr also said it could be difficult for policymakers to distinguish structural labour-market changes from ordinary cyclical weakness in real time. The same caution applies to company analysis. A staffing reduction could reflect automation, weaker demand, outsourcing or several causes together. It should not automatically be labelled an AI productivity gain.
Automated investment tools require identity and custody checks
The Cryptoaiml and TSAI allegations show why an AI label should increase scrutiny rather than replace it. Before relying on an automated investment service, check the legal entity, regulator record, custody arrangements, withdrawal terms and whether independently verifiable trades exist.
Do not give remote access, private keys, recovery phrases or verification codes to someone offering to recover an investment or release a withdrawal. A credible research workflow should preserve source records and calculations while keeping trading, transfers and account changes outside an automated system’s permissions unless separately authorised.
What to Watch Next
- 30 September at 08:00 UTC: Bitget scheduled USDT withdrawal restoration on Ethereum, BNB Smart Chain, Solana and Tron. Check a fresh network-specific notice before treating the timetable as completed.
- 30 September, US data: the August personal consumption expenditures price index was due after this briefing’s cut-off. Compare the released inflation components with a newly timed Treasury yield rather than assuming a market direction.
- 2 October at 08:00 UTC: Bitget scheduled restoration for other coins, fiat and peer-to-peer services. Confirm the exact asset and route inside the account.
- Next China releases: look for evidence that September’s PMI improvement extends to employment, medium-sized businesses and smaller manufacturers.
- Next US sessions: compare the 10-year Treasury yield, euro-dollar rate and the same Brent delivery contract at clearly identified times.
- Aave governance: distinguish community discussion, any later vote and completed deployment. The Sentora framework was still a proposal at the cut-off.
This briefing provides educational information, not personalised investment, trading, tax or legal advice.
Correction and update, 30 September 2026: The original UK Market Update incorrectly stated that no suitable company announcement had been available before the 06:10 BST news cut-off. Vesuvius had announced a possible offer on 29 September. We replaced that statement with the announcement and added Tuesday’s UK and US market closes. We also clarified Governor Barr’s remarks and linked Bitget’s dated Ethereum withdrawal notice. The original news cut-off and fixed market readings are unchanged.
Explore the live Bitcoin chart and Fear & Greed indicator
Optional live context
The briefing above is a fixed, dated snapshot. These provider displays update independently and may show different values. They do not change the article’s archived figures.
Bitcoin chart: daily candles, US dollars
TradingView · Bitstamp BTC/USD · London timezone. Each candle shows one day’s opening, high, low and latest or closing price. The latest candle is still forming. This is one exchange, not CoinGecko’s aggregated quote. Check the provider’s displayed time and data status.
The chart loads separately and may take a moment to appear. If it stays blank or looks stale, use the source-chart link below or hide the chart area. The dated market table remains readable without it.
Open the Bitcoin source chart on TradingView ↗
JavaScript is disabled. Use the Bitcoin source-chart link above.
Latest provider Fear & Greed indicator
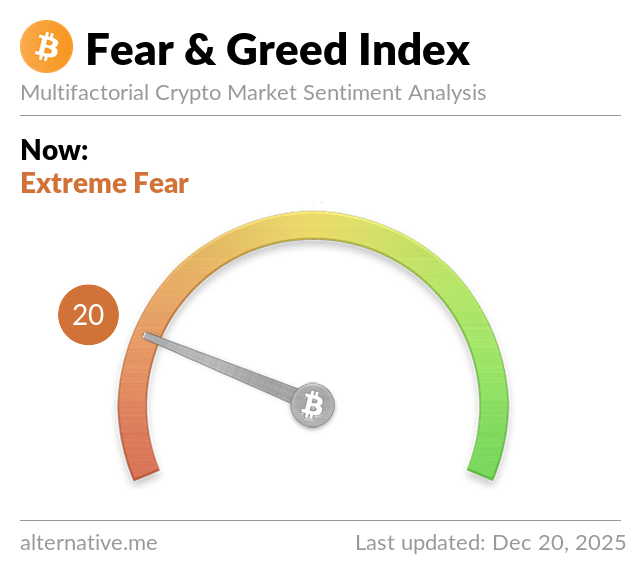
Sentiment image unavailable. Use the provider link above; the dated reading in the article remains available.