Default pension funds explained: a practical UK guide
Default pension funds explained for UK savers: check your investments, retirement date, charges and withdrawal assumptions before changing your pension.
A default pension fund is where your pension savings are invested when you have not chosen another option. Leaving that choice to the scheme can be sensible. Leaving its assumptions unchecked is a different matter.
What is a default pension fund?
In a defined contribution pension, contributions build an invested pot whose value depends on payments in, investment performance and charges. A default fund is the scheme’s ready-made investment option for people who do not select their own funds. It may be a single fund or a strategy using several funds.
This guide concerns UK defined contribution pensions, particularly workplace schemes. It is not about the State Pension or choosing investments inside a defined benefit pension, such as a final salary scheme.
MoneyHelper’s investment guide explains that defaults are usually designed around the needs of a broad membership. Professional management does not make them personally tailored, and neither your pot nor its future income is guaranteed.
The useful starting question is not “Should I leave the default?” It is “What is this default trying to do, and do its assumptions still match my plans?”
What happens to money in the default?
It is normally invested, not simply parked in a bank account until you make a decision. The portfolio may combine company shares, bonds, property and other assets. Shares are stakes in businesses; bonds are loans to governments or companies. The actual mix depends on your scheme and, sometimes, your stage in its investment strategy.
Default does not mean unmanaged. For trust-based schemes, The Pensions Regulator’s investment guidance describes trustees’ responsibilities for designing, monitoring and reviewing default arrangements. That oversight is different from an adviser assessing your individual finances.
Your provider’s fund factsheet shows the investments and risks; its strategy guide explains how your pension moves between them. You may need both. Our guide to reading a fund factsheet helps you interpret holdings, charges and performance without treating the biggest return as the whole story.
Lifestyle and target-date strategies explained
Many defaults change the investment mix as a selected retirement date approaches. The aim is to prepare the pot for its expected use, rather than leave the same exposure in place indefinitely.
A lifestyle strategy commonly switches money between funds according to a timetable. A target-date fund usually groups savers around an expected retirement year and changes the investments within that fund over time. Terminology overlaps: read the scheme’s description rather than relying on the label.
For example, Aviva’s auto-switching range includes approaches targeting an annuity, cash or drawdown, with availability depending on the pension plan. These are examples of different objectives, not recommendations or a claim that every Aviva member has those choices.
Nest Retirement Date Funds work around an expected withdrawal year. Nest says its consolidation phase starts roughly ten years before that date, reducing exposure to higher-risk markets. It also has arrangements for money left at the retirement date. That is Nest’s approach, not a universal timetable.
Do not assume every default ends entirely in cash or is designed to buy an annuity. Find out what yours targets, when changes start and what happens if you leave the money invested beyond its selected date.
Check the retirement date your provider uses
Your selected retirement date is an investment-planning input. It is not necessarily the day you stop working, your State Pension age or the earliest date the law and scheme rules allow you to access your pension. Changing an account setting does not override those access rules. MoneyHelper distinguishes the different pension ages and explains why the date held by your provider matters.
Consider a hypothetical saver, Alex, aged 55. The provider’s record says 65, but Alex now expects to start using this pot at 70. Suppose this fictional strategy starts changing the investment mix ten years before the selected age.
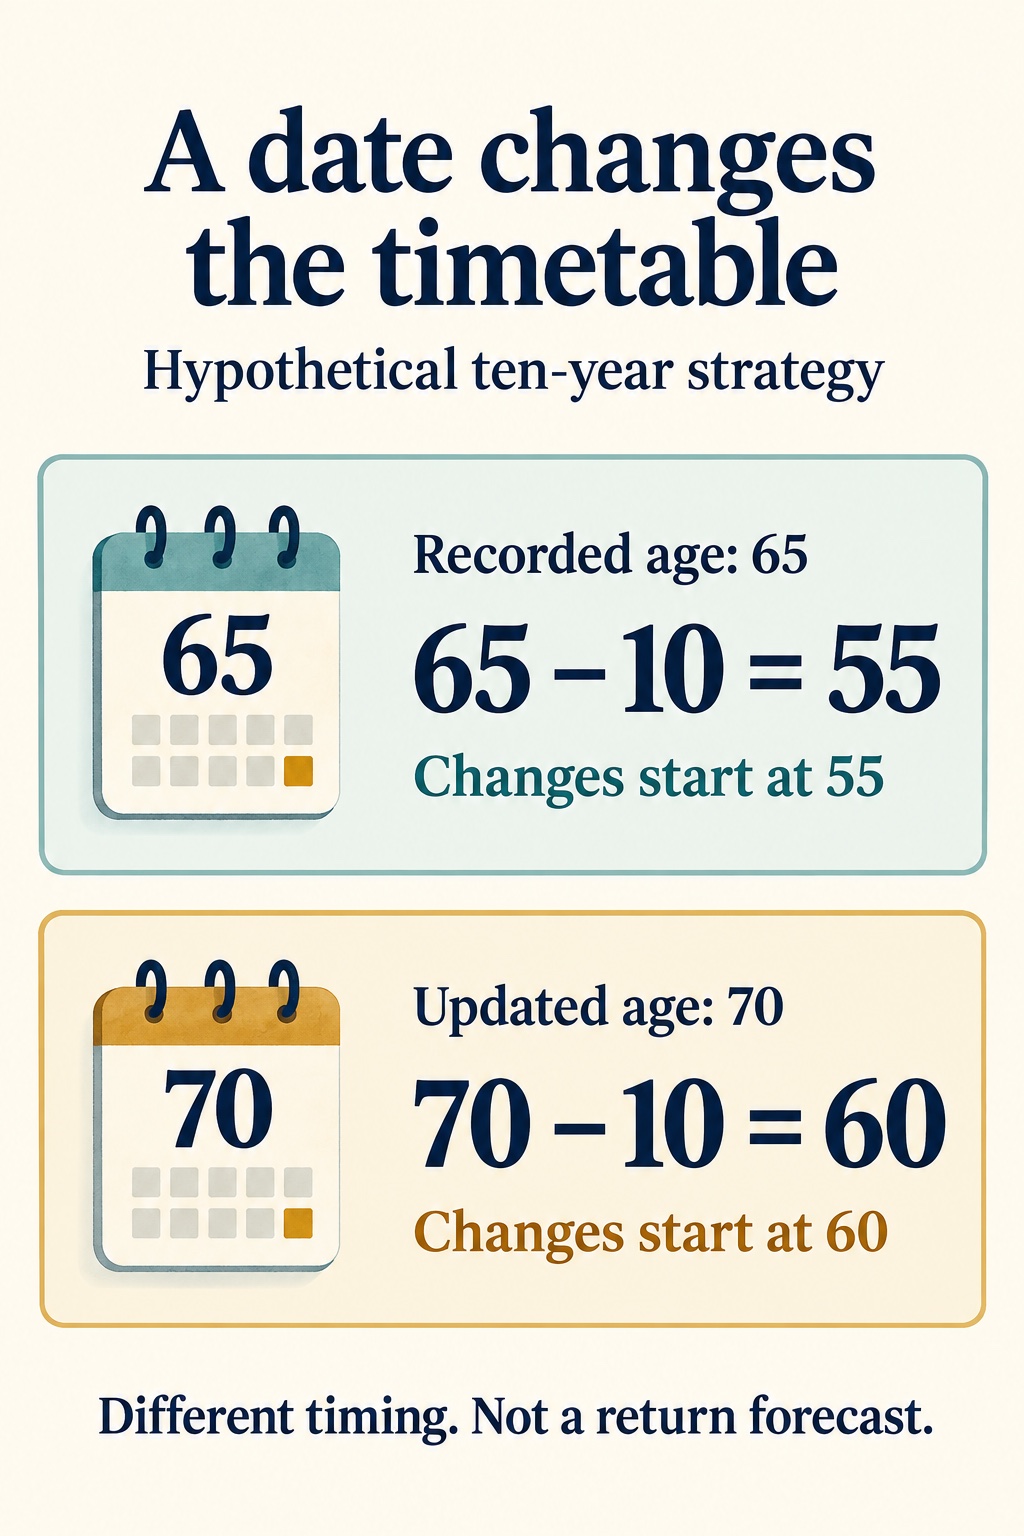
With 65 on the record, the change starts at 55: 65 minus ten. With 70 recorded, it would start at 60: 70 minus ten. A five-year difference in the setting changes the timetable by five years. It does not tell us which investments Alex should hold or predict a better return.
Alex’s next step is to ask what changing the date would actually do in this scheme. Some strategies respond by changing current holdings, not just future instructions. The ten-year period here is an example, not a rule to apply to your own pension.
How you take the money matters too
Two people planning to use their pensions in the same year may need the money to do different jobs. MoneyHelper’s retirement investment guide explains why the way you take your pension affects investment decisions.
- Buying an annuity: you exchange some or all of the pot for a guaranteed income on the annuity’s terms. A strategy targeting that purchase has a different objective from one intended to support ongoing withdrawals.
- Using drawdown: you take money while the rest remains invested. That remaining money may need to last for many years; market losses and withdrawals can reduce it, and it can run out.
- Taking cash: money you intend to withdraw soon has a different time horizon from money you expect to leave invested. Taking a lump sum can have tax consequences, so check those before acting.
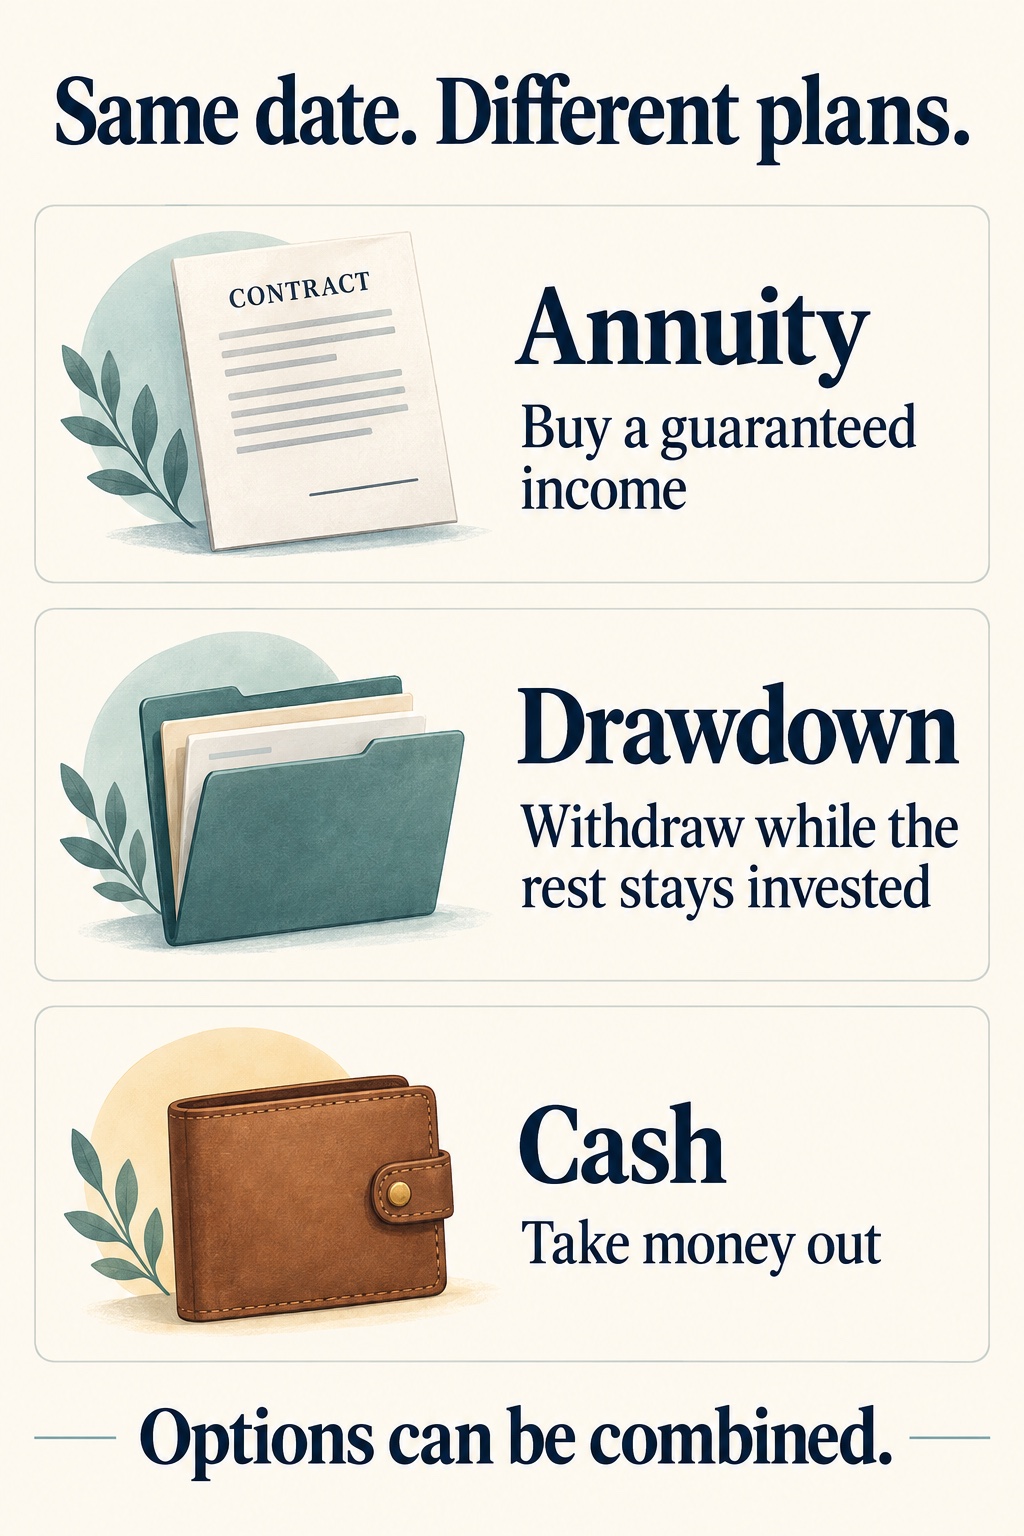
These are not three compulsory, all-or-nothing choices. People can combine methods or use them at different times. A default designed for flexibility is also not automatically suitable for every combination. Ask which outcome your strategy assumes and whether the scheme supports the option you have in mind. Our annuity versus drawdown comparison explores the income trade-offs in more detail.
Does reducing risk mean the pension cannot fall?
No. Moving away from shares may reduce one kind of exposure while leaving others. Bond holdings can fall when interest rates rise; cash can lose spending power when prices rise faster than the interest it earns. Keeping more in shares leaves greater exposure to stock-market falls. There is no setting that removes every risk.
A pension risk score is not a guarantee or a personal suitability test either. Our fund risk ratings guide explains why the method and written warnings matter alongside the number.
When you see “de-risking”, ask: reducing which risk, over what period, and for which intended use? Preparing for a near-term purchase is not the same task as supporting decades of withdrawals.
Should you stay in the default or choose your own funds?
Staying is a legitimate choice, not evidence that you have neglected your pension. Choosing your own funds is not automatically an upgrade. It gives you more responsibility for the mix, monitoring it and deciding whether it should change over time.
Investigate if your expected withdrawal date has changed, the strategy targets a different use from the one you intend, or its risks are not ones you understand or can accept. Those are reasons to seek answers, not automatic instructions to switch. A disappointing quarter, by itself, does not explain whether the strategy is doing the wrong job.
Check costs on your actual plan. Ask the provider to explain the total charges and which fund, administration or other costs are already included. Do not add a component fee twice or assume the cheapest headline percentage describes the most suitable option.
Changing investments within a pension is separate from opting out of the pension or transferring it to another provider. Do not stop contributions or move the whole pension merely to investigate the default. Transfers can involve costs or lost benefits and require a separate assessment.
A practical default-fund checklist
Open your pension account and its latest documents. Make a short note of these six answers:
- Exact option: what is the full fund or strategy name, and am I actually in the default?
- Current investments: what does it hold now, and which factsheet describes my current stage?
- Selected date: which retirement age or year is recorded, and does it reflect when I expect to use this pot?
- Timetable and destination: when does the mix change, what withdrawal outcome does it target, and what happens after the selected date?
- Costs: what do I pay in total under my plan, and what is included in each quoted figure?
- Changes: what would updating the date or choosing another strategy do to existing money and future contributions?
If something is missing, send the provider a specific question: “My account shows retirement at 65, but I expect to start drawing this pot at 70. What would updating that date change now, and what withdrawal method does my current strategy target?”
For help understanding withdrawal options, Pension Wise offers free guidance appointments for people aged 50 or over with a UK defined contribution pension, with some exceptions for younger people. Guidance explains options; it does not recommend a particular fund. For a recommendation based on your circumstances, consider an authorised financial adviser.
In plain English
You do not need to become a fund manager to check your default pension. Find its name, its date and its intended destination. If those assumptions still fit, doing nothing can be an informed decision. If they do not, understand the consequences before changing the settings.
This article is general financial education, not personal pension, investment or tax advice. Investments can fall as well as rise, and you may get back less than you invest.