Market Daily: Informa agrees £2.24bn Clarion deal as the S&P 500 sets a record and Bitcoin slips below $84,000
Informa agrees a £2.24bn Clarion deal, the S&P 500 sets a record, gilt yields ease and Bitcoin dips below $84,000. Markets briefing for 7 October 2026.
MARKET DAILY · MARKETS, TECHNOLOGY AND CRYPTO · 7 October 2026
Updated 12:52 BST, 7 October 2026
Digitally generated conceptual header, not a real event or a forecast. News cut-off 7 Oct 2026, 06:15 BST; sources checked through 7 Oct 2026, 06:15 BST; the fixed crypto observations are timed separately below.
Informa has agreed to buy the events business Clarion from Blackstone for an enterprise value of £2.24 billion, funded in part by a £940 million share placing, while the S&P 500 closed at a record high for the first time since August, the Nasdaq set a second straight record and UK gilt yields eased ahead of the 28 October Budget. Early on Wednesday, Bitcoin dropped below $84,000 as oil prices rose on reports of further attacks on tankers near the Strait of Hormuz.
This is Cristoniq’s Market Daily for Wednesday 7 October 2026. Sources were checked up to 06:15 BST on 7 October. Figures taken from data providers are given with the provider and observation time. Figures quoted from news reports carry the time or session the report gave; where a provider gives only a date and no time, as Investing.com and Trading Economics do for gilt yields, we say so. Percentage changes marked “Cristoniq calculation” are our own arithmetic from the stated provider’s figures. Weekly changes run from the Friday 25 September close to the Friday 2 October close and are labelled as such. Index closes are from Yahoo Finance; other providers may differ by a few points.
The day ahead
The main scheduled event is the release of the minutes of the Federal Reserve’s 15 to 16 September meeting. The Federal Reserve’s October calendar lists the minutes at 2:00 pm on 7 October. The calendar page does not state a time zone; Fed releases follow Washington time, which would make that 19:00 BST, after this edition is published. The same calendar lists the Fed’s monthly consumer credit data at 3:00 pm (20:00 BST). The US Treasury also auctions $39 billion of 10-year notes, a reopening, closing at 1:00 pm EDT (18:00 BST), per TreasuryDirect.
In London, Informa’s new shares from Tuesday’s placing are expected to begin trading at 8:00 am BST on or around Thursday 8 October, according to the company’s result of equity issue announcement.
On the crypto side, the Fear and Greed Index reading for 7 October is 71, labelled “Greed”, down from 73 on 6 October. The index is Alternative.me’s daily blend of volatility, volume, social media and other signals, with 0 meaning extreme fear and 100 extreme greed.
UK Market Update
The FTSE 100 closed at 10,541.70 on Tuesday 6 October, according to Yahoo Finance (observed 16:35 BST). That is 43.80 points, or 0.42 per cent, above Monday’s close of 10,497.90 (Cristoniq calculation), a third straight daily gain. The FTSE 250 closed at 24,215.30 per Yahoo Finance (observed 16:35 BST), up 91.50 points or 0.38 per cent from 24,123.80 (Cristoniq calculation). On a Friday-to-Friday basis, the FTSE 100 fell 2.18 per cent from 10,695.30 on 25 September to 10,462.00 on 2 October, and the FTSE 250 fell 0.28 per cent from 24,261.10 to 24,194.20 (Cristoniq calculations from Yahoo Finance daily closes).
Trading Economics said in its commentary for the 6 October session that the index extended its rebound from a three-month low as a pause in bond selling lifted global equities, with Unilever and Coca-Cola Europacific Partners up about 2 per cent, HSBC, Lloyds and NatWest up between 0.8 and 1.7 per cent, and Rolls-Royce down 2.69 per cent (Yahoo Finance’s closes of 1,478p and 1,438.20p give 2.69 per cent; Sharecast gives 2.25 per cent against its own reference price). Trading Economics put Informa’s gain at 5.2 per cent, but Yahoo Finance shows the shares closed up 2.95 per cent at 887.20 pence, so that figure appears to be intraday.
Defence sell-off. BAE Systems was the FTSE 100’s biggest faller, down 4.08 per cent at 1,855p, with Melrose down 2.97 per cent and Babcock down 2.07 per cent; in the FTSE 250, QinetiQ fell 5.38 per cent and Chemring 4.42 per cent, according to Sharecast’s closing report (17:17 BST, 6 October). Sharecast linked the falls, Rolls-Royce’s included, to a report in The Times that Prime Minister Andy Burnham is considering delaying a decision on when to increase defence spending until the autumn of next year, so that the review can take place alongside the next Budget. Whitbread was the index’s biggest riser, up 5.15 per cent at 2,551p; Sharecast gave no reason for the move.
Informa buys Clarion. Informa announced at 7:00 am on 6 October that it has agreed to acquire Clarion, a business-to-business events group, from Blackstone for an enterprise value of £2.24 billion. Enterprise value is the price for the business including its debt. Because Clarion is privately owned there is no share-price premium to measure; Informa says the price is 11.1 times Clarion’s expected 2027 EBITDA (earnings before interest, tax, depreciation and amortisation), falling to about 9 times after targeted cost synergies of about £50 million a year and about 8 times after revenue synergies of about £25 million of operating profit by 2029. Informa says the deal is funded by a placing of about £940 million of new shares (about 9 per cent of its issued share capital), dedicated acquisition financing and a pause in its share buyback, with completion expected in the fourth quarter of 2026 subject to regulatory approvals. The company also said it has “formally launched a separation process” for its Taylor & Francis academic publishing arm, with the outcome to be reported alongside its 2026 full-year results in March 2027. Stephen A. Carter, Group Chief Executive, said the planned separation “coincides with further expansion in B2B through the £2.24bn acquisition of Clarion”. The placing result showed 109,302,326 new shares sold at 860 pence, a discount of about 0.2 per cent to the 862 pence closing price on 5 October, raising about £940 million gross. The company said the placing price was also a discount of about 4.3 per cent to the 899 pence middle-market price at the time the price was agreed. Why it matters: Proactive Investors reported that Bloomberg Intelligence analyst Tom Ward described the price as reasonable and said the multiple of about 11 times expected 2027 EBITDA broadly matches comparable transactions (Proactive’s paraphrase, not a direct quotation).
Clarkson raises guidance. Shipbroker Clarkson said in a trading statement on 6 October that it now expects full-year underlying profit before tax of not less than £135 million after strong trading in August and September. The company said its broking division “delivered revenues significantly ahead of previous expectations” and that its financial division’s performance was “also being significantly up on expectations”. The shares closed up 2.18 per cent at 5,160p, from 5,050p, on Yahoo Finance daily closes (Cristoniq calculation).
Bank of England’s Mann on inflation. Reuters reported (via Yahoo Finance, 11:18 BST on 6 October) that Monetary Policy Committee member Catherine Mann told a conference hosted by TS Lombard that “inflation has become embedded” in the British economy, and that she was particularly concerned that inflation looked set to reach 4 per cent around the turn of the year, when most employers negotiate annual pay rises. Reuters said Mann has voted for quarter-point rate rises at recent meetings. Bank Rate is 3.75 per cent: the Monetary Policy Committee held it there on 17 September by six votes to three, with Mann, Megan Greene and Huw Pill preferring a rise to 4 per cent, according to the Bank’s minutes. Her comments are one member’s view, not a committee decision.
Other UK items. The Competition and Markets Authority published on 6 October the full text of its decision clearing E.ON’s proposed acquisition of OVO Energy at Phase 1, a decision announced on 1 October; the case page lists the inquiry as launched on 2 September. Separately, Daily Business reported on 6 October that Andy Agathangelou, founder of the Transparency Task Force, called on Financial Conduct Authority chair Ashley Alder to resign over the regulator’s handling of complaints from a whistleblower, Simon Andreisz, who took his own life. Daily Business reported that Alder said non-executive director Lea Paterson would lead an independent inquiry, and that FCA Chief Executive Nikhil Rathi defended the regulator’s whistleblowing processes, saying it handles about 1,300 cases a year.
US Market Update
The S&P 500 closed at 7,818.93 on Tuesday 6 October per Yahoo Finance (observed 16:40 EDT), up 44.98 points or 0.58 per cent from Monday’s 7,773.95 (Cristoniq calculation). The Nasdaq Composite closed at 27,599.79 per Yahoo Finance (observed 18:31 EDT), up 122.48 points or 0.45 per cent (Cristoniq calculation). The Dow Jones Industrial Average closed at 51,521.28 per Yahoo Finance (observed 16:42 EDT), up 253.38 points or 0.49 per cent (Cristoniq calculation). Yahoo Finance’s live blog for Tuesday described the S&P 500 close as a record high and the Nasdaq close as a back-to-back record.
Chips lead. Reuters reported (via MarketScreener, 6 October) that Marvell Technology raised its revenue target for fiscal 2028 (FY28, the company’s financial year ending in early 2028) to about $20 billion, above Wall Street expectations of $18.2 billion, and set a fiscal 2031 target of $70 billion to $90 billion. Marvell closed up 5.81 per cent at $287.01, from $271.25, on Yahoo Finance daily closes (Cristoniq calculation); Reuters’ 6 per cent and the Yahoo Finance live blog’s roughly 8 per cent were intraday readings. Reuters said Broadcom gained 4 per cent. Reuters quoted Marvell president and chief operating officer Chris Koopmans: “We have a track record of doing what we said we’re going to do.” The Yahoo live blog also said Nvidia and AMD reached new highs.
Google and Constellation nuclear deal. Constellation Energy announced on 6 October a 20-year power purchase agreement with Google under which Constellation will invest more than $4.3 billion to add 890 megawatts of capacity through upgrades at 11 of its nuclear units in Illinois, Pennsylvania and New Jersey, with the first upgrade expected by 2028. The companies also signed a separate 15-year supply agreement for 2,700 megawatts from Constellation’s existing fleet in the PJM grid, which serves the US mid-Atlantic and parts of the Midwest. Constellation shares closed up 12.25 per cent at $300.40, from $267.62, on Yahoo Finance daily closes (Cristoniq calculation); the Yahoo Finance live blog’s 13 per cent was an intraday reading. Why it matters, in the companies’ own framing: Constellation chief executive Joe Dominguez said the collaboration “can serve as a model for how technology companies and the energy industry can work together to responsibly develop the digital economy”, while the deal is a claim about future investment rather than a completed build.
Rates and the Fed. Vice Chair for Supervision Michelle Bowman gave a speech on modernising regulation and supervision on 6 October. For the policy path, today’s minutes are the main event; see What to Watch Next.
Global Markets
Europe. Trading Economics said in its commentary for 6 October that the STOXX Europe 600 rose 0.5 per cent to 636.6 and the Euro STOXX 50 rose 0.5 per cent to 6,274, a third consecutive gain, helped by lower long-dated euro-area sovereign yields and banks, with BNP Paribas up 2.5 per cent and UniCredit, Santander and Deutsche Bank up 1.5 per cent each. Its France page put the CAC 40 at 7,865, up 0.40 per cent, with Schneider Electric the worst performer after its PTC acquisition, which we covered in Tuesday’s edition. Trading Economics gives dates but no times for these closes.
ECB. The European Central Bank published an interview with chief economist Philip Lane, conducted by Ansa on 1 October and released on 6 October, in which he said “the dominant issue in terms of interest rate policy so far has been the energy shock” and that “the strength of the pass-through to the rest of the economy remains uncertain”. Lane said the ECB had not yet seen strong second-round effects on inflation.
Asia on Wednesday. Trading Economics showed the Nikkei 225 at 70,235 during Wednesday 7 October trading (read at about 06:15 BST, before the Tokyo close at 07:30 BST), down 448.98 points or 0.64 per cent from Tuesday’s close, as investors took profits after the prior session’s three-month high, with Kioxia, Advantest and Disco among the decliners. Its Hong Kong page, read at about 06:15 BST, showed the Hang Seng at 24,134 during Wednesday trading, down 145 points or 0.6 per cent, and said mainland Chinese markets remained closed for the National Day holiday. Trading Economics attributed the Hong Kong weakness to Brent moving back above $101 a barrel after a storm threatened US Gulf oil facilities and Houthi attacks on targets in Saudi Arabia.
Bonds, Currencies and Commodities
Gilts. Investing.com’s historical data shows the UK 10-year gilt yield at 5.399 per cent for 6 October, down from 5.429 per cent on 5 October, a fall of about 3 basis points (Cristoniq calculation; a basis point is one hundredth of a percentage point). Investing.com gives daily figures without times. Trading Economics showed the 30-year gilt yield at 5.91 per cent for 6 October, down 0.04 percentage points on the day, again with a date but no time. Trading Economics’ gilt news feed reported on 1 October that the 30-year yield had reached 6 per cent for the first time since 1998, and in a 6 October item that the 10-year yield eased to 5.35 per cent after reaching its highest since July 2007 the previous week. Why it matters: a higher 10-year yield raises the cost of new government borrowing and feeds into fixed-rate mortgage pricing, which is why the level matters for Chancellor John Healey’s Budget on Wednesday 28 October, the date HM Treasury confirmed on 31 July. Tuesday’s small fall does not reverse the rise of recent weeks.
US Treasuries. The US 10-year yield was 5.269 per cent per Yahoo Finance (observed 14:59 EDT on 6 October), down from 5.311 per cent on 5 October, a fall of about 4 basis points (Cristoniq calculation). CoinDesk reported at 00:00 EDT on 7 October that the yield had climbed 3 basis points to 5.31 per cent in overnight trading, so the two figures are from different sessions. Trading Economics said the 10-year was steadying near 24-year highs as traders awaited the Fed minutes.
Sterling and the euro. Sterling was $1.3248 per Yahoo Finance (observed 06:14 BST on 7 October), compared with Tuesday’s close of $1.3274 (Yahoo Finance daily data), so sterling slipped overnight. The euro was $1.1233 per Yahoo Finance (observed 06:14 BST), compared with $1.1264 at Tuesday’s close, so the euro also slipped.
Oil. Brent crude futures were $101.43 a barrel per Yahoo Finance (observed 06:04 BST on 7 October), up $0.85 or 0.85 per cent from Tuesday’s close of $100.58 (Cristoniq calculation). WTI crude futures were $90.05 per Yahoo Finance (observed 06:05 BST), up $0.61 or 0.68 per cent from $89.44 (Cristoniq calculation). Trading Economics said on 7 October that Iran had intensified attacks on tankers in the Strait of Hormuz in recent days, with UK Maritime Trade Operations reporting nine incidents so far this month, while Saudi Arabia’s East-West pipeline had restored capacity to 5.8 million barrels a day. Al Jazeera reported on 6 October, citing Kpler, that Gulf oil flows excluding Iran recovered to more than 81 per cent of pre-war levels in September and that about 40 per cent of exports now bypass the strait. The pre-war baseline refers to the US-Israel war on Iran that began on 28 February 2026, after which Iran effectively closed the strait and the US blockaded Iranian ports, Al Jazeera said in the same report. Al Jazeera quoted Tamas Varga of PVM Oil Associates attributing the recovery to “the effective use of the East-West pipeline by Saudi Arabia and ship-to-ship transfer”.
Gold and copper. COMEX gold futures were $4,162.90 an ounce per Yahoo Finance (observed 06:05 BST on 7 October), down $24.20 or 0.58 per cent from Tuesday’s $4,187.10 (Cristoniq calculation). COMEX copper futures were $6.631 a pound per Yahoo Finance (observed 06:04 BST), with no day-on-day change given because Yahoo Finance’s daily data and its quote page showed different reference closes for Tuesday.
Crypto
Bitcoin below $84,000. Bitcoin was $84,160 per CoinGecko at 06:13 BST on 7 October, down 1.77 per cent over 24 hours, with a 24-hour low of $83,648 and high of $86,648. Ether was $2,613.61, down 3.32 per cent, XRP $1.47, down 2.54 per cent, Solana $118.39, down 1.44 per cent, and Chainlink $13.62, down 1.59 per cent, all over the same 24 hours. These five assets are a selection, not the whole market. CoinDesk reported at 00:00 EDT on 7 October that Bitcoin traded near $86,600 on Tuesday before a sharp drop early on Wednesday took it to about $83,840, and linked the move to Iranian tanker attacks lifting oil prices, Treasury yields and the dollar. The Fed raised its target range by a quarter point to 3.75 to 4.00 per cent on 16 September, by a 12 to 0 vote, according to its statement. CoinDesk quoted Dan Khus of LVRG Research on the Fed minutes: “The market had already priced in that hike, so traders are now looking at whether the notes sound patient or still point to one more increase before the end of the year.” The Block reported at 23:57 EDT on 6 October that crypto liquidations reached $555.6 million over 24 hours, including $487.2 million of long positions, citing CoinGlass. A liquidation is the forced closure of a leveraged position when losses eat through its collateral; our Crypto Decoded guides explain leverage and liquidations in more detail.
CRYPTO MARKET PICTURE · FIXED SNAPSHOT
Five crypto assets, one clear view
| Asset | USD price | 24h change | Magnitude (0 to 4 per cent) |
|---|---|---|---|
| BTC Bitcoin |
$84,160.00 | -1.77 per cent | |
| ETH Ethereum |
$2,613.61 | -3.32 per cent | |
| SOL Solana |
$118.39 | -1.44 per cent | |
| XRP XRP |
$1.47 | -2.54 per cent | |
| LINK Chainlink |
$13.62 | -1.59 per cent |
Powered by CoinGecko. Retrieved 7 Oct 2026, 06:15 BST. Provider observation times: BTC 7 Oct 2026, 06:13 BST; ETH 7 Oct 2026, 06:13 BST; SOL 7 Oct 2026, 06:13 BST; XRP 7 Oct 2026, 06:13 BST; LINK 7 Oct 2026, 06:13 BST. Bars compare the size of changes on a shared 0 to 4 per cent scale, not prices or capitalisation. Signs show direction. This selected crypto sample is not a picture of all crypto assets or wider financial markets; these archived quotes do not update.
UK names digital gilt banks. HM Treasury announced on 6 October that Barclays, HSBC, Lloyds, Morgan Stanley, NatWest and RBC Capital Markets have been appointed joint lead managers for DIGIT, the Digital Gilt Instrument, a short-dated government bond to be issued through the Digital Securities Sandbox with pilot issuance expected in the first quarter of 2027. The Treasury describes DIGIT as a pilot separate from the government’s main debt programme, so it does not change how ordinary gilts are issued. Economic Secretary to the Treasury Lucy Rigby KC MP called the appointment “an important step as we work towards issuance early next year”. In a speech the same day, Rigby said regulations will bring “a broad range of cryptoasset activities within the FCA regulatory perimeter from 25 October 2027” and that the application window for firms seeking transitional arrangements opened on 30 September. She said: “The challenge now is not proving that the technology works. It is creating the conditions in which markets can adopt it at scale.”
Short-dated prediction contracts. Crypto Briefing reported on 6 October that Coinbase has launched price prediction contracts for US users on whether Bitcoin, Ether, Solana, BNB and other tokens will rise or fall over windows as short as 15 minutes, paying $1 if correct and nothing if not, offered through Coinbase Financial Markets and not available in all states, with Nevada named as an exception. DeFi Rate reported, citing Reuters, that Kalshi launched a perpetual futures contract on a US 500 stock index on Tuesday 6 October, following an August regulatory filing. A perpetual future has no expiry date and uses periodic funding payments between long and short holders to keep its price near the index. Coinbase’s contracts are all-or-nothing, so the most a buyer can lose is the price paid; Kalshi’s perpetual lets investors take leveraged positions in either direction, DeFi Rate reported. Our Investing Basics section explains why leverage magnifies losses as well as gains.
AI, Technology and Investor Tools
OpenAI to watermark text in the EU. TechCrunch reported on 5 October that OpenAI will add an invisible watermark to text generated by ChatGPT and Codex for users in the European Union over the coming weeks to meet the EU AI Act’s transparency requirements, and has made the same feature available to API developers worldwide as an opt-in setting that is off by default. TechCrunch said the method, which OpenAI calls textGrain, shapes the model’s word choices so that a detector can recognise the pattern. OpenAI’s own caveats, as reported by TechCrunch, are that replacing 10 per cent of words with synonyms cut detection from 92 per cent to 66 per cent, that short passages, maths answers and translated text are harder to detect, and that watermarks “can indicate that an OpenAI system generated or processed part of a passage, but not how much human judgment, editing, or creativity went into it”. For readers, that means a missing watermark does not prove a text was written by a person.
ASOS customer data incident. The National Cyber Security Centre said on 6 October that ASOS customers had received an unauthorised push notification and that the retailer had said “basic personal information including name and contact details may have been accessed”, but not “payment card information or account passwords”. The NCSC advised customers to watch for suspicious messages, avoid clicking links in them, and use passkeys or strong unique passwords with two-step verification. ASOS’s account of what was and was not accessed is the company’s own statement, as relayed by the NCSC. ASOS shares closed down 9.56 per cent at 454p, the FTSE 250’s biggest fall, according to Sharecast’s closing report and Yahoo Finance.
Marvell and Constellation. Both stories, covered in the US section, rest on the same demand: Marvell’s $20 billion FY28 target assumes continued spending on custom AI chips, and Constellation’s 890 megawatts of upgrades is sized for the data-centre load Google has contracted for 20 years. For investors the point is that the AI build-out now runs through electricity supply as well as semiconductors, which is why the utility’s shares moved more on Tuesday than the chipmaker’s did.
What to Watch Next
Times are from the official calendars linked. UK times are BST; US times are Eastern (EDT) with the BST equivalent in brackets, unless the source does not state a zone.
- Wednesday 7 October: Fed minutes of the 15 to 16 September meeting at 2:00 pm, then consumer credit (G.19) at 3:00 pm, per the Federal Reserve calendar, which does not state a time zone; if Eastern, the minutes land at 19:00 BST, after this edition is published.
- Thursday 8 October: Informa’s new shares expected to be admitted at 8:00 am BST, per the company’s announcement. Tesco’s interim results for the half year are expected the same day, according to the Express & Star and an IG preview. The US Treasury’s $22 billion 30-year bond reopening auction closes at 1:00 pm EDT (18:00 BST), per TreasuryDirect. Fed Governor Christopher Waller speaks on the economic outlook in Istanbul at 4:30 am EDT (09:30 BST), per the Fed calendar.
- Friday 9 October: the CMA’s invitation to comment on the BT / TalkTalk merger closes, per the case page.
- Wednesday 14 October: US consumer price index for September at 8:30 am EDT (13:30 BST), per the Bureau of Labor Statistics schedule, then the Fed’s Beige Book at 2:00 pm EDT (19:00 BST).
- Thursday 15 October: ONS GDP monthly estimate for August 2026 at 7:00 am.
- Friday 16 October: Fed industrial production for September at 9:15 am EDT (14:15 BST).
- Monday 19 October: the CMA’s report on the BT / TalkTalk merger is due to the Secretary of State by 5:00 pm, per the case page.
- Tuesday 20 October: next ONS labour market overview, a date stated in the September bulletin; the bulletin does not give a release time.
- Wednesday 21 October: ONS consumer price inflation for September at 7:00 am and public sector finances for September at 7:00 am.
- Friday 23 October: ONS retail sales for September at 7:00 am.
- Tuesday 27 to Wednesday 28 October: Federal Open Market Committee meeting, with a press conference at 2:30 pm EDT (19:30 BST) on 28 October, per the Fed calendar. The UK Budget is also on 28 October, per HM Treasury.
- Thursday 29 October: US third-quarter GDP advance estimate and personal income and outlays for September, both at 8:30 am EDT (13:30 BST), per the Bureau of Economic Analysis schedule; the September international trade report follows on Wednesday 4 November at 8:30 am EDT (13:30 BST).
This article is general, non-personalised information for education only. It is not investment, tax or legal advice and does not take account of your circumstances. Figures are as observed at the stated times from the named sources and may have changed. Cristoniq does not recommend any investment and you should seek regulated advice before making financial decisions. Capital is at risk.
Correction and update, 7 October 2026: An earlier version gave Monday’s levels as Tuesday’s closes for sterling and the euro, which reversed the direction of both moves; Tuesday’s closes were $1.3274 and $1.1264. The copper day-on-day change was removed because the source’s reference closes conflicted. The Nikkei 225 figure was an intraday reading, not a close, and is now described as such. The Trading Economics gilt reports were re-dated (the 6 per cent 30-year yield on 1 October; the 10-year easing to 5.35 per cent on 6 October). Informa’s 5.2 per cent gain was an intraday figure; the shares closed up 2.95 per cent. Analyst Tom Ward’s remarks were Proactive Investors’ paraphrase, not a direct quotation, so the quotation marks were removed. The news cut-off and fixed market readings are otherwise unchanged. Later on 7 October: the Nikkei 225 level was corrected to 70,235 (70,683.98 less 448.98) and its read time added; the gilt news links now point to the dated 6 October item and the Budget date is sourced to HM Treasury; the prediction-contract sentence now distinguishes Coinbase’s all-or-nothing contracts from Kalshi’s leveraged perpetual; the Fed’s 16 September rise to 3.75 to 4.00 per cent, the Bank of England’s 3.75 per cent Bank Rate and a line on the conflict behind the oil figures were added for context; the defence sell-off, the reason for Rolls-Royce’s fall and the biggest FTSE 100 riser were added from Sharecast’s closing report, and “Coca-Cola” now reads Coca-Cola Europacific Partners; Marvell and Constellation now carry closing moves rather than intraday ones; Informa’s 4.3 per cent discount to 899 pence and the Clarkson and ASOS share moves were added; the liquidation figure now comes from The Block citing CoinGlass; the watchlist gained Tesco’s results, the US Treasury auctions and the CMA’s BT / TalkTalk deadlines, with UK times for US events; and three repetitive passages were cut.
Explore the live Bitcoin chart and Fear & Greed indicator
Optional live context
The briefing above is a fixed, dated snapshot. These provider displays update independently and may show different values. They do not change the article’s archived figures.
Bitcoin chart: daily candles, US dollars
TradingView · Bitstamp BTC/USD · London timezone. Each candle shows one day’s opening, high, low and latest or closing price. The latest candle is still forming. This is one exchange, not CoinGecko’s aggregated quote. Check the provider’s displayed time and data status.
The chart loads separately and may take a moment to appear. If it stays blank or looks stale, use the source-chart link below or hide the chart area. The dated market table remains readable without it.
Open the Bitcoin source chart on TradingView ↗
Latest provider Fear & Greed indicator
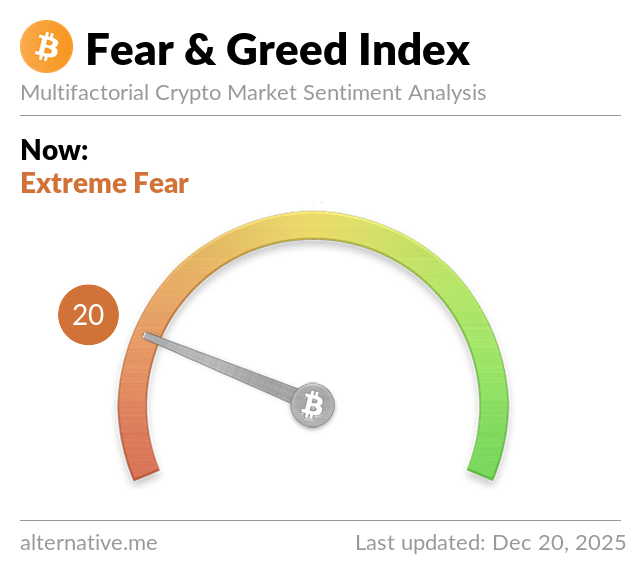
Sentiment image unavailable. Use the provider link above; the dated reading in the article remains available.