Market Daily: UK borrowing overshoots as chip shares rally and oil retreats
UK borrowing exceeded forecast, chip shares rallied, bond yields stayed near 5%, Brent retreated and the ECB launched tokenised settlement infrastructure.
MARKET DAILY · MARKETS, TECHNOLOGY AND CRYPTO · 2026-09-22
Digitally generated conceptual header, not a real event or a forecast. News cut-off 22 Sept 2026, 08:07 BST; sources checked through 22 Sept 2026, 08:14 BST; the fixed crypto observations are timed separately below.
The day ahead
Britain begins Tuesday with public borrowing above the official forecast. The public sector borrowed £18.3 billion in August, £2.9 billion more than a year earlier and £3.5 billion above the Office for Budget Responsibility forecast, according to the Office for National Statistics.
The monthly overshoot matters ahead of the Budget on 28 October because it adds pressure to the government’s fiscal choices. It does not, by itself, determine taxes, spending or gilt prices. Year-to-date borrowing was lower than a year earlier, while still exceeding forecast, so the monthly and cumulative comparisons point in different directions.
In Monday’s markets, semiconductor shares advanced while oil and government-bond yields retreated. These developments occurred during the same session, but that does not establish one cause for every price move. Expensive energy and borrowing remain constraints even after a one-day decline.
The research cut-off was 08:07 BST on Tuesday 22 September. Reuters’ traditional-market figures below were open-market observations last updated at 11:55 EDT on Monday, not official closing levels. Crypto prices were observed at about 08:05 BST on Tuesday and retrieved at 08:07 BST. Markets and updating provider displays may since have changed.
UK Market Update
Borrowing rises as spending outpaces receipts
Public sector net borrowing, the difference between public spending and public income, was £18.3 billion in August 2026. That was 19% more than in August 2025 and the second-highest August figure in the comparable monthly series, without adjusting for inflation. The ONS cautions that recent estimates can be revised.
Central government current receipts increased by £3.3 billion from a year earlier to £89.8 billion. Total central government expenditure rose by £4.9 billion to £103.1 billion. The larger increase in spending helps explain why borrowing rose despite higher receipts.
Debt interest payable was £8.8 billion, the highest August amount since monthly records began in 1997, without adjusting for inflation. Of this, £2.1 billion reflected the accrued capital uplift on index-linked gilts. These gilts have payments linked to the Retail Prices Index, so inflation can add volatility to the recorded interest bill. Accrued means the cost is recognised over time, although the capital uplift is paid when the gilt is redeemed.
Three views of the UK borrowing position
- The month: August borrowing was £18.3 billion, £3.5 billion above forecast.
- The financial year so far: borrowing from April to August was £77.3 billion, £2.2 billion below the same period last year but £8.1 billion above forecast.
- The balance sheet: public sector net debt was provisionally £2,985.5 billion at the end of August, equivalent to 93.8% of gross domestic product.
Gross domestic product, or GDP, measures the size of the economy. Expressing debt as a share of GDP helps comparison over time, but it does not show the interest rate paid or when debt must be refinanced.
Kingfisher raises its full-year guidance
Kingfisher, the owner of B&Q and Screwfix, reported adjusted pre-tax profit of £404 million for the six months to 31 July, up 9.9% from a year earlier. The company also raised its full-year adjusted pre-tax profit guidance to £595 million to £635 million, from £565 million to £625 million, and increased its free-cash-flow guidance to £480 million to £520 million.
The results were released at 07:00 BST, before this briefing’s 08:07 BST news cut-off. The higher guidance is evidence that management expects a stronger full year, but it remains a company forecast rather than completed profit or cash generation. The official release also says a £14 million one-off UK business-rates refund contributed to first-half profit, so readers should distinguish that benefit from the underlying trading improvement.
For gilt investors, the release provides evidence about the government’s financing position without mechanically determining gilt prices. Inflation expectations, Bank of England policy, debt-auction demand and the maturity of new borrowing also matter. The next major fiscal test is whether the 28 October Budget changes tax, spending or borrowing plans.
US Market Update
Chipmakers lead the advance, but yields remain demanding
At 11:55 EDT on Monday, while the US cash market was open, Reuters reported the S&P 500 up 1.05%, the Nasdaq Composite up 1.62% and the Dow Jones Industrial Average up 0.49%. These were intraday percentage changes, not closing figures.
Advanced Micro Devices was up 9.2% at the same observation and had reached a reported market capitalisation of US$1 trillion. Intel was up 13% and Micron Technology 2.3%. Market capitalisation is the share price multiplied by shares outstanding. Reaching a round-number valuation is notable, but it does not establish what a company will earn or whether its shares are attractively valued.
Reuters connected the wider technology advance with evidence of strong demand for computing used in artificial intelligence. Investors still need to separate three questions: whether chip demand is expanding, whether an individual company can supply the right products profitably, and how much expected growth is already reflected in its share price.
The ten-year US Treasury yield remained close to 5% during the session. That raises the return available from government debt and can reduce the present value assigned to company profits expected far into the future. Strong industry demand does not remove financing costs, competitive pressure or valuation risk.
Global Markets
The ECB moves tokenised settlement into live infrastructure
The European Central Bank said its Pontes service launched on 21 September. Pontes is designed to settle tokenised assets in central bank money. Tokenisation uses distributed-ledger technology to represent ownership of, or a claim on, an asset. Settlement is the final exchange of the asset and payment after a trade.
Central bank money is a direct claim on a central bank rather than a commercial institution. Using it for settlement can reduce one form of counterparty exposure, but it does not remove risks associated with the security, trading venue, technology or custody arrangement.
The ECB also launched preparatory work to invest a small portion of its own funds in tokenised securities, with purchases intended to settle through Pontes. Initial investments would focus on euro-denominated securities issued by euro-area public bodies and European supranational institutions.
The distinction matters. Pontes has launched, but the investment programme has not. The ECB’s Executive Board will determine operational details and timing after preparatory work. This is evidence of institutional development, not evidence that the central bank already holds a substantial tokenised-securities portfolio.
The next useful measures will be completed settlement activity, participating institutions and reliability under meaningful transaction volumes. Availability of infrastructure is not the same as sustained adoption.
Global shares rise, led by technology
Reuters recorded the MSCI All-World index up 1.03% and European shares up 1.12% during Monday’s open session. These broad observations do not mean that every country or sector advanced. The large moves in selected semiconductor shares are important when interpreting a rising global benchmark.
South Korea supplied a more direct measure of the chip cycle. Provisional Korea Customs Service figures showed exports of US$71.4 billion in the first 20 days of September, up 78.3% from the same period a year earlier. Semiconductor exports reached US$34.1 billion, a record for this part of the month. These are early customs figures rather than a complete September total, but they add real-economy evidence to the market’s enthusiasm for chipmakers.
The same release recorded 15.5 working days in the 2026 period, compared with 16.5 a year earlier, and said average daily exports rose 89.8%. No fresh Japanese cash-equity figure is included because Tokyo was closed for the Silver Week holiday.
Bonds, Currencies and Commodities
Treasury yields ease but remain near 5%
The benchmark ten-year US Treasury yield was 4.959% during Monday’s session, down 3.68 basis points, according to Reuters. The two-year yield was 4.731%, down 1.18 basis points. A basis point is one-hundredth of a percentage point.
When a conventional bond’s yield falls, its market price generally rises. The one-session decline does not remove the wider effect of borrowing costs close to 5%. Treasury yields influence corporate refinancing, mortgage pricing and the discount rates used to value shares.
During the same open session, Germany’s ten-year government-bond yield was 3.451%, down 7.08 basis points, while France’s was 4.465%, down 10 basis points. France’s higher yield indicates that investors demanded more compensation to hold its debt, but one daily move cannot provide a complete diagnosis of fiscal or political risk.
Reuters reported that concern about inflation and long-term public finances had pushed France’s risk premium to its widest since the 2012 euro-area debt crisis on Friday. It also noted that German Chancellor Friedrich Merz’s conservative party had suffered its worst election result since 1949. Those developments help explain why investors were paying particular attention to European government debt, although Reuters identified falling oil prices as the main force behind Monday’s broader bond rally.
Brent retreats towards US$100 as reported export flows recover
Brent crude futures were US$100.17 per barrel during Monday’s open market, down 3.56% on the day, according to Reuters. US crude was US$95.49 per barrel, down 4.8%. These were US-dollar prices per barrel observed during trading, not official settlement prices.
Reuters reported that data from Kpler showed Saudi exports recovering to just over four million barrels per day so far in September, after falling to 2.4 million barrels per day in August. It also reported efforts to restart flows through Saudi Arabia’s east-to-west pipeline after damage, while noting that details were limited and analysts remained uncertain.
Improving reported export flows can reduce immediate scarcity concerns, but the regional supply outlook remains uncertain. Brent near US$100 is still consequential for transport, manufacturing, household energy costs and inflation expectations. A producer and an energy-intensive customer experience the same oil move differently.
The dollar strengthens against the yen
Reuters recorded the US dollar up 0.36% against the Japanese yen at ¥157.43 per dollar during Monday’s open foreign-exchange session. The report noted reduced liquidity during Japan’s three-day Silver Week holiday. Currency trading continued even though Japan’s domestic holiday affected local-market conditions.
No sufficiently identified and timed gold or copper observation was available in the retained evidence. Numerical claims for those commodities have therefore been omitted.
Crypto
Five selected assets rise, but the sample is not the market
At approximately 08:05 BST on Tuesday, CoinGecko recorded all five selected crypto assets higher over the preceding rolling 24 hours. XRP had the largest percentage increase in the sample at 5.74%, followed by Bitcoin at 4.56%. Solana rose 3.80%, Chainlink 2.66% and Ether 2.45%.
These are rolling percentage comparisons whose starting points change continually. They describe five selected assets at one observation time, not the whole cryptocurrency market or wider financial markets. Their timing does not establish that equity, oil or regulatory developments caused the moves.
Five crypto assets, one clear view
| Asset | USD price | 24h change | Magnitude |
|---|---|---|---|
| BTC Bitcoin |
$85,331.00 | +4.56% | |
| ETH Ethereum |
$2,729.57 | +2.45% | |
| SOL Solana |
$116.54 | +3.80% | |
| XRP XRP |
$1.52 | +5.74% | |
| LINK Chainlink |
$12.90 | +2.66% |
Powered by CoinGecko. Retrieved 22 Sept 2026, 08:07 BST. Provider observation times: BTC 22 Sept 2026, 08:05 BST; ETH 22 Sept 2026, 08:05 BST; SOL 22 Sept 2026, 08:05 BST; XRP 22 Sept 2026, 08:05 BST; LINK 22 Sept 2026, 08:05 BST. Bars compare the size of changes on a shared 0–6% scale, not prices or capitalisation. Signs show direction. This selected crypto sample is not a picture of all crypto assets or wider financial markets; these archived quotes do not update.
The accompanying Bitcoin-focused sentiment reading was 78, classified by its provider as Extreme Greed, compared with 70 the previous day. It is a fixed daily mood indicator, not an intraday trading signal, valuation model or forecast.
Pontes links tokenised assets with central bank money
The ECB’s Pontes launch is also a consequential crypto-infrastructure development because it applies distributed-ledger technology within regulated wholesale finance. It differs from an open cryptocurrency network: the service is intended to settle tokenised assets in central bank money.
The practical issue is coordination between the security and cash sides of a transaction. If an asset moves on one system while payment depends on another process, delays or mismatches can create risk. Pontes provides infrastructure intended to connect those legs, although evidence of success must come from completed transactions and sustained use.
Catena receives preliminary conditional approval
The US Office of the Comptroller of the Currency granted Catena Trust Bank preliminary conditional approval on 18 September. The proposed national trust bank plans to provide custody, investment-management, trust, conversion, clearing and execution services involving fiat currency, securities and digital assets, including payment stablecoins that comply with the GENIUS Act once it takes effect.
This is not final authority to open. The OCC decision letter says final approval depends on Catena satisfying pre-opening requirements and allows the regulator to modify, suspend or withdraw the preliminary approval. Among its conditions, the proposed bank must maintain at least US$10 million of tier-one capital and meet specified liquidity requirements.
Check the route before moving crypto
Several potentially important stablecoin, decentralised-finance and security reports were excluded because their product terms, regulatory status or loss figures could not be verified from retained evidence.
For an actual transfer, the asset, receiving address and blockchain network must agree. A small test transfer can limit the value exposed to an addressing or compatibility error. Cristoniq’s first-transfer runbook explains how to check the destination, network, fee and transaction record before sending the balance.
AI, Technology and Investor Tools
Amazon blocks Meta’s Muse shopping agent
Amazon has blocked Meta’s Muse personal AI agent from shopping on Amazon.com for users. In original reporting by GeekWire, Amazon said Muse accessed its store without prior agreement, did not identify itself as an agent and created privacy and security concerns. These are Amazon’s allegations; Meta had not responded to GeekWire by the report’s publication time.
Meta’s Muse launch material says the agent can use a browser to complete tasks, asks before sensitive actions such as purchases and stores credentials so the agent cannot see them. Amazon’s block does not prove that Meta’s safeguards failed. It shows that technical capability, user permission and platform permission are separate questions.
That distinction matters as people use AI agents for shopping, research and financial workflows. An agent may be able to navigate a website but still lose access if the platform objects to automation, identity disclosure or handling of customer data. Before relying on an AI tool for a consequential task, check whether the service supports that integration, what information the agent can reach and where final user approval is required.
What to Watch Next
- 21 October 2026: the ONS is due to publish its next UK public-finance release. Look for revisions to August and whether cumulative borrowing remains above the official forecast.
- 28 October 2026: the UK Budget and accompanying Office for Budget Responsibility forecast should show how the government intends to respond to the borrowing path.
- Timing not yet determined: the ECB’s Executive Board will decide the operational details and timing of its proposed tokenised-securities investments after preparatory work. Do not treat preparation as a completed purchase.
- Ongoing: evidence of Pontes adoption should come from completed settlement activity and sustained institutional use, rather than launch announcements alone.
Updated 22 September 2026: Added Kingfisher’s pre-cut-off results, South Korean trade data and the Amazon-Meta Muse dispute; clarified Catena’s preliminary conditional approval and the context for European bond moves. The 08:07 BST news cut-off and archived market figures are unchanged.
This briefing is educational information, not personalised investment, trading, tax or legal advice.
Explore the live Bitcoin chart and Fear & Greed indicator
Optional live context
The briefing above is a fixed, dated snapshot. These provider displays update independently and may show different values. They do not change the article’s archived figures.
Bitcoin chart: daily candles, US dollars
TradingView · Bitstamp BTC/USD · London timezone. Each candle shows one day’s opening, high, low and latest or closing price. The latest candle is still forming. This is one exchange, not CoinGecko’s aggregated quote. Check the provider’s displayed time and data status.
The chart loads separately and may take a moment to appear. If it stays blank or looks stale, use the source-chart link below or hide the chart area. The dated market table remains readable without it.
Open the Bitcoin source chart on TradingView ↗
JavaScript is disabled. Use the Bitcoin source-chart link above.
Latest provider Fear & Greed indicator
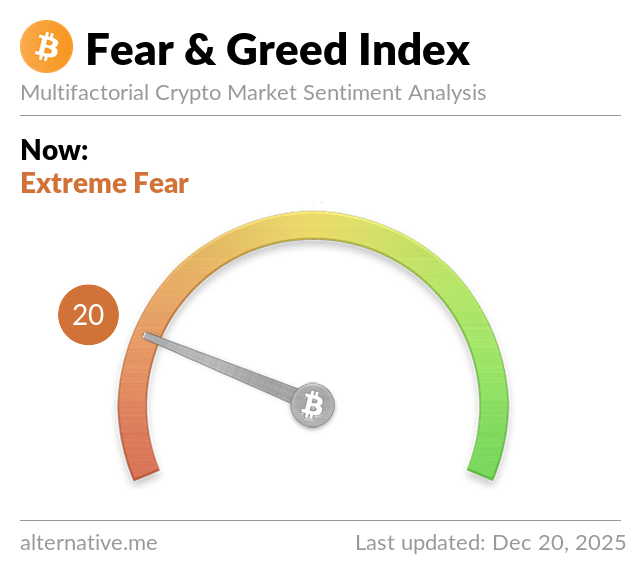
Sentiment image unavailable. Use the provider link above; the dated reading in the article remains available.