Market Daily: Nike’s index exit, UK dealmaking and AI’s next move
Nike leaves the S&P 100 as sportswear fortunes diverge. Plus UK deals, bonds and commodities, crypto infrastructure, and new AI tools for investors.
MARKET DAILY · MARKETS, TECHNOLOGY AND CRYPTO · 2026-09-21
Research cut-off: 21 September 2026, 08:14 BST (07:14 UTC). Traditional-market closes are from Friday 18 September where stated. Crypto observations: 08:06 BST; retrieved 08:08 BST. Supplementary provider displays update independently.
The day ahead
Nike leaves the S&P 100 today, putting a familiar consumer brand on the wrong side of a changing US stock market. Kylian Mbappé’s move from Nike to Swiss challenger On adds a more tangible competitive story: established brands are facing rivals with growing sales and ambitions beyond running. Ahead of JD Sports’ results this week, the answer matters to UK investors too.
Britain starts the week with a different mix of opportunities and pressures: an ambitious technology acquisition, a smaller copper explorer moving towards a cash payment, and retailers preparing to explain how much customers are really spending. Japan has raised rates, Vietnam’s market promotion takes effect, and the price of borrowing remains central to the outlook.
In crypto, the useful developments go beyond another green price table. Circle’s new blockchain, Aave’s proposed custody-based lending and Coinbase’s stock-futures filing offer three different versions of the connection between traditional finance and crypto. We finish with what new AI document tools and a TradingView broker connection actually change for someone researching investments.
UK Market Update
A difficult Friday, followed by a useful test of consumer demand
The FTSE 100 finished Friday 18 September at 10,659.13, down 1.5% on the day. The FTSE 250 fell 0.6% to 24,205.42, while the AIM All-Share, covering London’s smaller-company AIM market, rose 0.4% to 796.09, according to AJ Bell’s closing report. These are last-session closes, not Monday morning prices. The contrast is a reminder that a weak blue-chip index does not describe every part of the UK market.
Friday’s ONS retail-sales release provides the backdrop for this week’s company reports. The volume of goods bought in Great Britain rose 0.5% in August after falling 0.5% in July. Over the three months to August, volumes were 0.9% higher than in the previous three-month period. Volume matters here: it measures the amount bought after adjusting for price changes, rather than simply counting more pounds passing through the till.
That is an improvement, but it does not tell us which retailers are winning customers or how much discounting they need. Kingfisher’s half-year results are scheduled for Tuesday 22 September; JD Sports’ half-year results follow on Wednesday 23 September. For Kingfisher, the useful questions are demand for home improvement and the balance between sales and margins. For JD, the sportswear brands discussed below make product mix, stock levels and full-price selling particularly worth following.
Craneware’s results show how a cyber incident can change the outlook
AIM-listed healthcare software company Craneware brings a more immediate test of technology-company resilience. Its 21 September results, reported by Daily Business, showed revenue of US$206 million for the year to 30 June and statutory profit before tax up 7% to US$25.8 million. But management reset revenue expectations for the following financial year to approximately US$185 million amid uncertainty after July’s cyber incident.
The company’s announcement says customer services and core operations were not disrupted, while the full financial consequences remain unquantified. That distinction matters: keeping a service running does not settle the cost of an incident or its effect on customer confidence. Investors need to separate the completed year’s profit improvement from the weaker forward outlook, then watch customer renewals, remediation costs and the company’s review of its cost base.
Softcat’s US expansion brings a bigger opportunity and a bigger execution test
Softcat’s agreement to buy Dallas-based General Datatech, or GDT, is one of the more consequential UK company developments carrying into this week. GDT announced the agreement on 17 September, bringing its data-centre and networking capabilities together with Softcat’s IT procurement and lifecycle services. The deal would give Softcat a larger platform for serving customers on both sides of the Atlantic.
Softcat’s adviser, Slaughter and May, puts the enterprise value at US$1.05 billion and describes funding from existing cash, approximately £350 million of new shares and new debt facilities. Enterprise value measures the business on a basis that takes debt and cash into account; it is not simply the amount handed to shareholders. Nor should a credit facility’s maximum size be confused with the amount already borrowed.
The commercial logic is straightforward. A business expanding its computing infrastructure may want one supplier capable of supporting offices and data centres in several countries. AI investment can add to that demand, but a larger addressable market does not automatically deliver better returns. Integration, staff retention, customer overlap and the cost of financing will determine how much of the opportunity reaches shareholders.
GDT says completion is expected no later than the end of the first quarter of calendar 2027, subject to regulatory filings and approvals. This is an agreed transaction still to complete. The next useful evidence is how the combined business converts its broader capabilities into profitable customer work.
Small caps: Galileo moves closer to a payment, not a completed windfall
Among smaller companies, Galileo Resources offers a concrete development to follow. Mining Weekly reported on 18 September that the conditions for selling the subsidiary holding two Botswana copper prospecting licences to a Sandfire subsidiary had been met. Completion is expected around 30 September.
Alliance News’ account distinguishes the US$3 million upfront payment from a possible US$20 million to US$80 million success payment tied to specified future copper-reserve thresholds. That distinction is the story for shareholders: progress towards an initial receipt is tangible, while the much larger contingent amount depends on future results. It is neither cash already received nor the value of a proven producing mine.
For an explorer, an asset sale can help fund work elsewhere without immediately issuing more shares. The next announcement should establish completion and the payment position. Subsequent accounts will show how the proceeds affect available cash and spending commitments.
US Market Update
Nike’s index exit is a prompt to examine the business
Wall Street ended Friday unevenly: the S&P 500 rose 0.2% to 7,650.50, the Nasdaq Composite gained 0.4% to 26,522.55 and the Dow fell 0.2% to 51,682.64. The Russell 2000 smaller-company index lost 0.5%. Those closing figures from AP show why a positive headline for the S&P 500 can coexist with a less comfortable session elsewhere.
Today’s corporate focus is Nike. S&P Dow Jones Indices’ 4 September notice removes Nike from the S&P 100 before US trading opens on Monday 21 September. Dell Technologies, Palo Alto Networks, Arista Networks and Sandisk join in the same rebalance. The index change is effective today; the announcement itself is not new.
The precise description matters. This is an exit from the S&P 100, a particular index of large US companies. It is not a stock-exchange delisting or, by itself, a finding that Nike has just become America’s 101st-largest company. Index membership follows the provider’s selection rules. Investors following that benchmark have a different reason to trade from someone assessing Nike’s prospects over several years.
Nike’s latest full-year results, released on 30 June, give a more useful business diagnosis. Revenue for the year to 31 May was US$46.4 billion, flat in reported dollars and down 2% after removing currency effects. In the final quarter, wholesale revenue, from selling through other retailers, rose 4% in reported terms, while Nike Direct, its own stores and digital business, fell 7%. A brand can improve its relationship with retailers while still struggling in the channels it controls.
Profit needs an equally careful reading. Nike’s fourth-quarter gross margin rose to 49.2%, but the company attributed approximately nine percentage points to expected US tariff recoveries. That benefit should be separated from the underlying trading performance.
Adidas and On show why “sportswear is struggling” is too broad
Adidas is an important counterexample. Its 30 July results showed second-quarter revenue rising 14% on a currency-neutral basis to €6.7 billion, with performance sport growing 39%, led by football and running. Gross margin also improved. Currency-neutral growth removes the translation effect of exchange-rate movements; it is useful when comparing a global company’s sales over time.
Puma’s position is different. Its 31 July release reported second-quarter sales down 9.4% on a currency-adjusted basis and an operating loss of €53.1 million. Puma attributed the sales decline to its reset measures and softer demand. Cutting unwanted wholesale business can depress revenue while management tries to rebuild the brand, so falling sales and a turnaround strategy can exist together. The strategy still has to produce sustainable improvement.
Meanwhile, Swiss challenger On reported second-quarter sales growth of 13.5% in Swiss francs, or 21.6% at constant currencies, in its 11 August release. These companies report in different currencies and across different financial periods, so their headline percentages are not a perfect league table. They do, however, challenge the idea that weak demand is affecting every sportswear business in the same way.
Four brands. Different business stories.
Look beneath the sector label to demand, sales channels and the cost of growth.
Wholesale improved in Q4; direct sales weakened.
Football and running helped drive performance-sport growth.
Reset measures and softer demand accompanied an operating loss.
Expansion into football is a future test, not the cause of these results.
Mbappé’s move connects Nike’s challenge directly to On’s ambitions
There is now a direct connection between the two companies. FourFourTwo reported on 18 September that Kylian Mbappé had ended his Nike partnership to join On. In its announcement that day, On confirmed the footballer would become a global ambassador and help develop and test football footwear and clothing. Thierry Henry has also been appointed Director of Football, while Barcelona player Sydney Schertenleib is involved in product development.
For On, this opens a route from running into another major sporting market, with recognisable athletes helping it reach new customers. For Nike, the loss of a prominent partner gives a concrete example of the competition for both athlete relationships and consumer attention. It is a separate business development from Nike’s index removal; neither establishes the cause of the other.
The next test is the product launch. On says its first football products will be available in 2027. Sponsorship can create attention before a boot reaches the shops, but the return depends on product appeal, distribution and repeat sales relative to the cost of expansion. This partnership cannot explain On’s already-reported second-quarter growth. It shows where the company wants to compete next.
For investors, the more revealing comparison is whether a company is selling desirable products at healthy prices, building repeat demand and controlling inventory. A famous logo is an advantage, not a permanent guarantee. JD’s results this week offer a retailer’s view of that competition, alongside the brands’ own accounts.
Global Markets
Vietnam’s promotion broadens its place in global benchmarks
Vietnam’s move from frontier to secondary emerging-market status in FTSE Russell’s classification takes effect today. It makes qualifying Vietnamese shares eligible for the provider’s major global equity benchmarks. Inclusion is phased across four tranches, beginning this September and concluding in September 2027.
The importance is practical. Funds following a benchmark must reflect its changing composition, while active managers often use those same indices as their reference point. Improved market access can therefore broaden the pool of potential investors. It does not make every Vietnamese share attractive or guarantee a one-day surge: the transition has been announced in advance and is deliberately gradual.
Anyone holding a global or emerging-market fund should distinguish the country’s new classification from the fund’s actual holdings. The benchmark followed, eligibility of individual shares and implementation timetable all affect the exposure that reaches a portfolio.
Japan’s higher rates matter beyond Japanese shares
The Bank of Japan voted 7–2 on Friday 18 September to guide the overnight call rate to around 1.25%. Japan’s equity market is closed for holidays from 21 to 23 September, according to the Japan Exchange Group calendar. A quote displayed during those days should not be mistaken for a fresh Tokyo cash-market session.
Higher Japanese borrowing costs matter internationally because investors can borrow in one currency to buy assets in another. That is a carry trade: its appeal depends on both the interest-rate gap and the exchange rate. More expensive yen funding can change the calculation, but it does not mean every such trade unwinds immediately. Currency moves and expectations about the next policy decision remain part of the picture.
Bonds, Currencies and Commodities
The policy rate and the cost of borrowing are different numbers
The Federal Reserve raised its target range to 3.75%–4% on 16 September. The Bank of England held Bank Rate at 3.75% the next day, with three of its nine policymakers preferring a quarter-point increase. The Bank said persistent or volatile energy prices increased the risk of inflation spreading into wages and other prices.
That helps explain why a policy-rate hold is not a promise of cheaper mortgages or company borrowing. Bond investors price a stream of future payments, taking account of expected inflation, future rates and the return they require for holding the debt. When an existing fixed-rate bond’s price falls, its yield rises. Longer-term borrowing costs can therefore increase even while the central bank leaves its current rate unchanged.
AJ Bell’s Friday London report quoted the ten-year gilt yield at 5.31%, against 5.21% on Thursday, and sterling at US$1.3372. These are dated market observations. For UK holders of unhedged overseas funds, exchange rates are another moving part: a stronger pound reduces the sterling value of an unchanged dollar asset, while a weaker pound increases it. A currency-hedged fund aims to reduce that effect, usually with costs and imperfect results.
Oil and gold are responding to more than one force
Reuters’ early Friday oil report described falling crude prices as concern about Saudi supply disruption eased, despite continuing conflict risks. Later in the London session, Brent was quoted at US$104.37 a barrel. The different observation times matter: an early-session fall and a later higher quote are not interchangeable descriptions of a closing price.
For businesses, expensive oil works through transport, manufacturing and household budgets. An airline buying fuel and a producer selling crude do not experience the same price change in the same way. For central banks, the additional question is whether an energy shock fades or starts influencing wider wage and price decisions.
Gold has a different balance of influences. Reuters reported that US gold futures settled 0.6% higher at US$4,424.90 per troy ounce on Friday. Gold pays no interest, so higher bond yields can make competing assets more appealing; demand for protection and changing expectations can pull the other way. A rise in gold following a rate increase is not a contradiction, nor does it establish that interest rates have stopped mattering.
Crypto
A stronger five-asset snapshot, with several different stories underneath
At 08:06 BST on Monday, CoinGecko’s observations put Bitcoin at US$81,620 and ether at US$2,664.54, up 1.65% and 3.53% respectively over the preceding 24 hours. All five assets in the table were higher, with Chainlink showing the largest percentage gain in this sample. That describes this selection and time window, rather than proving a recovery across the entire crypto market.
Five crypto assets, one clear view
| Asset | USD price | 24h change | Magnitude |
|---|---|---|---|
| BTC Bitcoin |
$81,620.00 | +1.65% | |
| ETH Ethereum |
$2,664.54 | +3.53% | |
| SOL Solana |
$112.32 | +3.35% | |
| XRP XRP |
$1.44 | +4.17% | |
| LINK Chainlink |
$12.57 | +4.91% |
Powered by CoinGecko. Retrieved 21 Sept 2026, 08:08 BST. Provider observation times: BTC 21 Sept 2026, 08:06 BST; ETH 21 Sept 2026, 08:06 BST; SOL 21 Sept 2026, 08:06 BST; XRP 21 Sept 2026, 08:06 BST; LINK 21 Sept 2026, 08:06 BST. Bars compare the size of changes on a shared 0–5% scale, not prices or capitalisation. Signs show direction. This selected crypto sample is not a picture of all crypto assets or wider financial markets; these archived quotes do not update.
Alternative.me’s fixed daily Bitcoin sentiment reading is 70, classified as Greed, one point below Sunday’s 71. Price and sentiment measure different things: a daily sentiment score is neither a valuation model nor evidence that the next move will be upwards.
Circle’s Arc launch makes the stablecoin infrastructure story tangible
Circle opened Arc’s public mainnet on 16 September. Mainnet means the operational network, rather than a testing environment. The company is bringing payments, tokenised assets and financial applications onto a blockchain designed around stablecoins, tokens intended to track an asset such as the US dollar.
Arc uses USDC to pay network transaction fees. That changes the experience of using it: someone making a payment need not first acquire a separate volatile asset solely to cover the network fee. USDC aims to track the US dollar, so this simplifies the dollar cost of transacting; it does not remove issuer, redemption, wallet or application risks.
The commercial test now moves from the launch roster to actual use. Institutions can announce integrations well before customers use them at meaningful scale. Payment volumes, reliable operation and activity that persists after launch incentives will be more informative than counting partner logos. For a reader comparing networks, the important distinction is between infrastructure being available and evidence of sustained demand.
Aave wants to connect institutional custody with on-chain borrowing
A separate Aave Labs governance proposal, posted on 14 September, would allow institutions to borrow stablecoins against assets held with Anchorage. Instead of transferring the underlying collateral into Aave, the proposed system represents it with a non-transferable receipt token. Chainlink infrastructure would synchronise the custodian’s records with the lending system.
This is a proposal for a separate Aave V4 lending environment, not a statement that every existing Aave market now accepts such collateral. Its appeal is that an institution could retain its custody arrangement while gaining access to blockchain-based borrowing. The trade-off is a dependency on several systems agreeing about the same position, particularly when falling collateral values require liquidation.
The governance decision, operating limits and handling of a default deserve as much attention as the integration itself. Keeping an asset with a custodian changes where it sits; it does not abolish the risk of borrowing against it.
Coinbase’s proposed stock perpetuals are exposure, not ownership
The SEC’s 18 September notice for Coinbase Derivatives covers proposed cash-settled futures on individual shares and exchange-traded funds, including perpetual contracts with no fixed expiry. The document says CFTC approval had not yet been granted and the proposed rule change was not yet effective. Its formal title includes “Immediate Effectiveness”, so reading the operative text matters.
A cash-settled contract pays gains or losses in money; it does not deliver the underlying share. Someone trading a contract linked to a company is therefore in a different position from a shareholder. Funding payments, contract terms and the treatment of corporate events can affect the outcome as well as the share price.
The development is consequential because a trading format familiar in crypto is being proposed for US share exposure. It should be assessed on its actual rules and approval status, rather than described as ordinary share ownership available around the clock.
Ethereum’s next upgrade is still a testing story
Ethereum’s Glamsterdam roadmap lists the Sepolia test-network fork for 6 October, with mainnet expected in the fourth quarter of 2026 and no confirmed mainnet date. That distinction prevents a test milestone from being mistaken for a change already applied to users’ transactions.
The Ethereum Foundation’s developer guidance explains a concrete part of the work: changes to the computational charges, known as gas, for creating and accessing stored network data. Tests found a small set of contracts whose assumptions could break or degrade under the new schedule, while the large majority were unaffected. Developers have work to do before activation; this is more specific than a blanket promise of cheaper transactions for everyone.
AI, Technology and Investor Tools
AI moves closer to the document where the investment case is written
Two updates last week point in the same useful direction. OpenAI announced ChatGPT for Word on 17 September, bringing document questions, drafting, selected-text revision and formatting into Word through its Microsoft add-in. The release notes say it is available across ChatGPT plans, including Free, with plan usage limits applying.
Anthropic announced on 16 September that Claude Cowork and chat were merging, alongside new Claude Docs and Slides tools. The combined experience is rolling out on Pro and Max over the following weeks; the document and presentation tools are in beta on paid plans, with enterprise administrators controlling access. An announcement date does not mean every account received every feature immediately.
For an investor, the opportunity is less copying between a chatbot and a research document. A useful starting task is to give the assistant two dated company updates and ask it to identify changes in revenue, margins, financing and management’s outlook, with the supporting passage beside each point. That creates a comparison a reader can inspect, rather than a confident verdict whose workings are hidden.
The Nike results illustrate why this matters. An assistant that notices the headline margin improvement but drops the tariff-recovery explanation can produce a polished but misleading investment note. Preserve the source, reporting period and qualifications when moving findings into a document. Neither product announcement establishes that the tool can predict returns or replace judgement about the business.
TradingView and Fidelity bring analysis and execution closer together
TradingView announced its Fidelity Investments connection on 10 September. Eligible Fidelity brokerage accounts can connect to Supercharts to trade supported US stocks and exchange-traded funds. An ETF is a fund whose shares trade on an exchange, often used to hold a basket of investments.
The practical gain is a shorter path from examining a chart to placing an order. This is a US brokerage integration, however, and should not be read as a promise that a UK Fidelity account can use it. Eligibility, account permissions and supported order types still matter.
A combined interface also makes it easier to act before finishing the research. The chart explains what a price has done; company filings explain what the business has reported. Connecting the two workflows is useful, but a technically convenient order is not necessarily a well-supported decision.
An official warning for technology workers
Japan’s National Police Agency announced a joint warning on 18 September, with authorities in the US, Australia and Germany, about the North Korea-linked WaterPlum group, also known as Contagious Interview. The announcement covers attack methods and activity involving North Korean IT workers. For readers working in technology or using a computer that also accesses financial accounts, unfamiliar recruitment software deserves scrutiny. Verify the organisation and instructions before running code, and never supply a wallet recovery phrase or private key as part of an interview or support request.
Let AI organise. Keep the evidence in view.
A practical sequence for checking an investment-related claim.
Open the filing or announcement. Record its date, financial period and whether it describes a proposal or a completed action.
Use AI to organise differences and suggest questions. Keep its interpretation separate from what the source actually says.
Check consequential numbers, units and qualifications against the original. A fluent answer is not verification.
What to Watch Next
- Monday 21 September: Nike’s S&P 100 removal takes effect before US trading opens; Vietnam begins its phased FTSE emerging-market inclusion.
- Tuesday 22 September: Kingfisher’s scheduled half-year results provide a company-level test of home-improvement demand.
- Wednesday 23 September: JD Sports’ scheduled half-year results bring the retailer’s perspective to the changing sportswear market.
- Thursday 24 September: Japan’s next regular equity session follows three exchange holidays and gives investors a fresh local session after last week’s rate decision.
- Around 30 September: Galileo expects completion of its Botswana licence transaction. Look for confirmation of completion and the initial payment, rather than counting contingent proceeds.
- 6 October: the Ethereum roadmap’s next Glamsterdam milestone is the Sepolia test-network fork, not mainnet activation.
The common question across this briefing is what an announcement changes in practice: the customers a business can reach, the cash it may receive, the assets a fund can hold or the work a tool can do. Those details are more useful than treating every new headline as an instruction to trade.
Explore the live Bitcoin chart and Fear & Greed indicator
Optional live context
The briefing above is a fixed, dated snapshot. These provider displays update independently and may show different values. They do not change the article’s archived figures.
Bitcoin chart: daily candles, US dollars
TradingView · Bitstamp BTC/USD · London timezone. Each candle shows one day’s opening, high, low and latest or closing price. The latest candle is still forming. This is one exchange, not CoinGecko’s aggregated quote. Check the provider’s displayed time and data status.
The chart loads separately and may take a moment to appear. If it stays blank or looks stale, use the source-chart link below or hide the chart area. The dated market table remains readable without it.
Open the Bitcoin source chart on TradingView ↗
JavaScript is disabled. Use the Bitcoin source-chart link above.
Latest provider Fear & Greed indicator
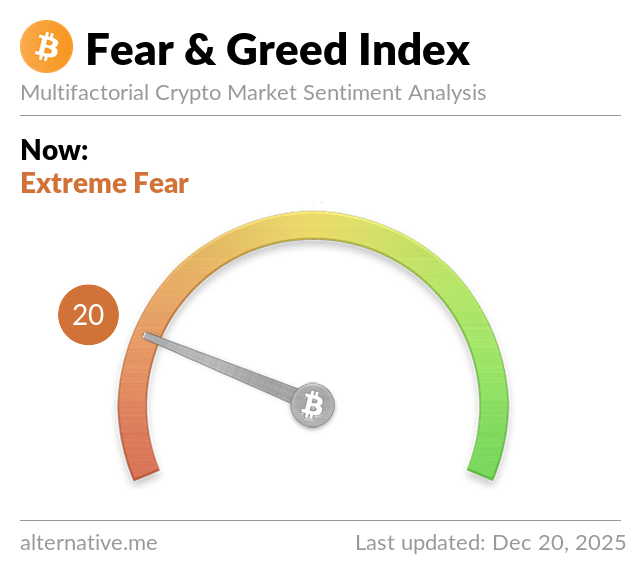
Sentiment image unavailable. Use the provider link above; the dated reading in the article remains available.